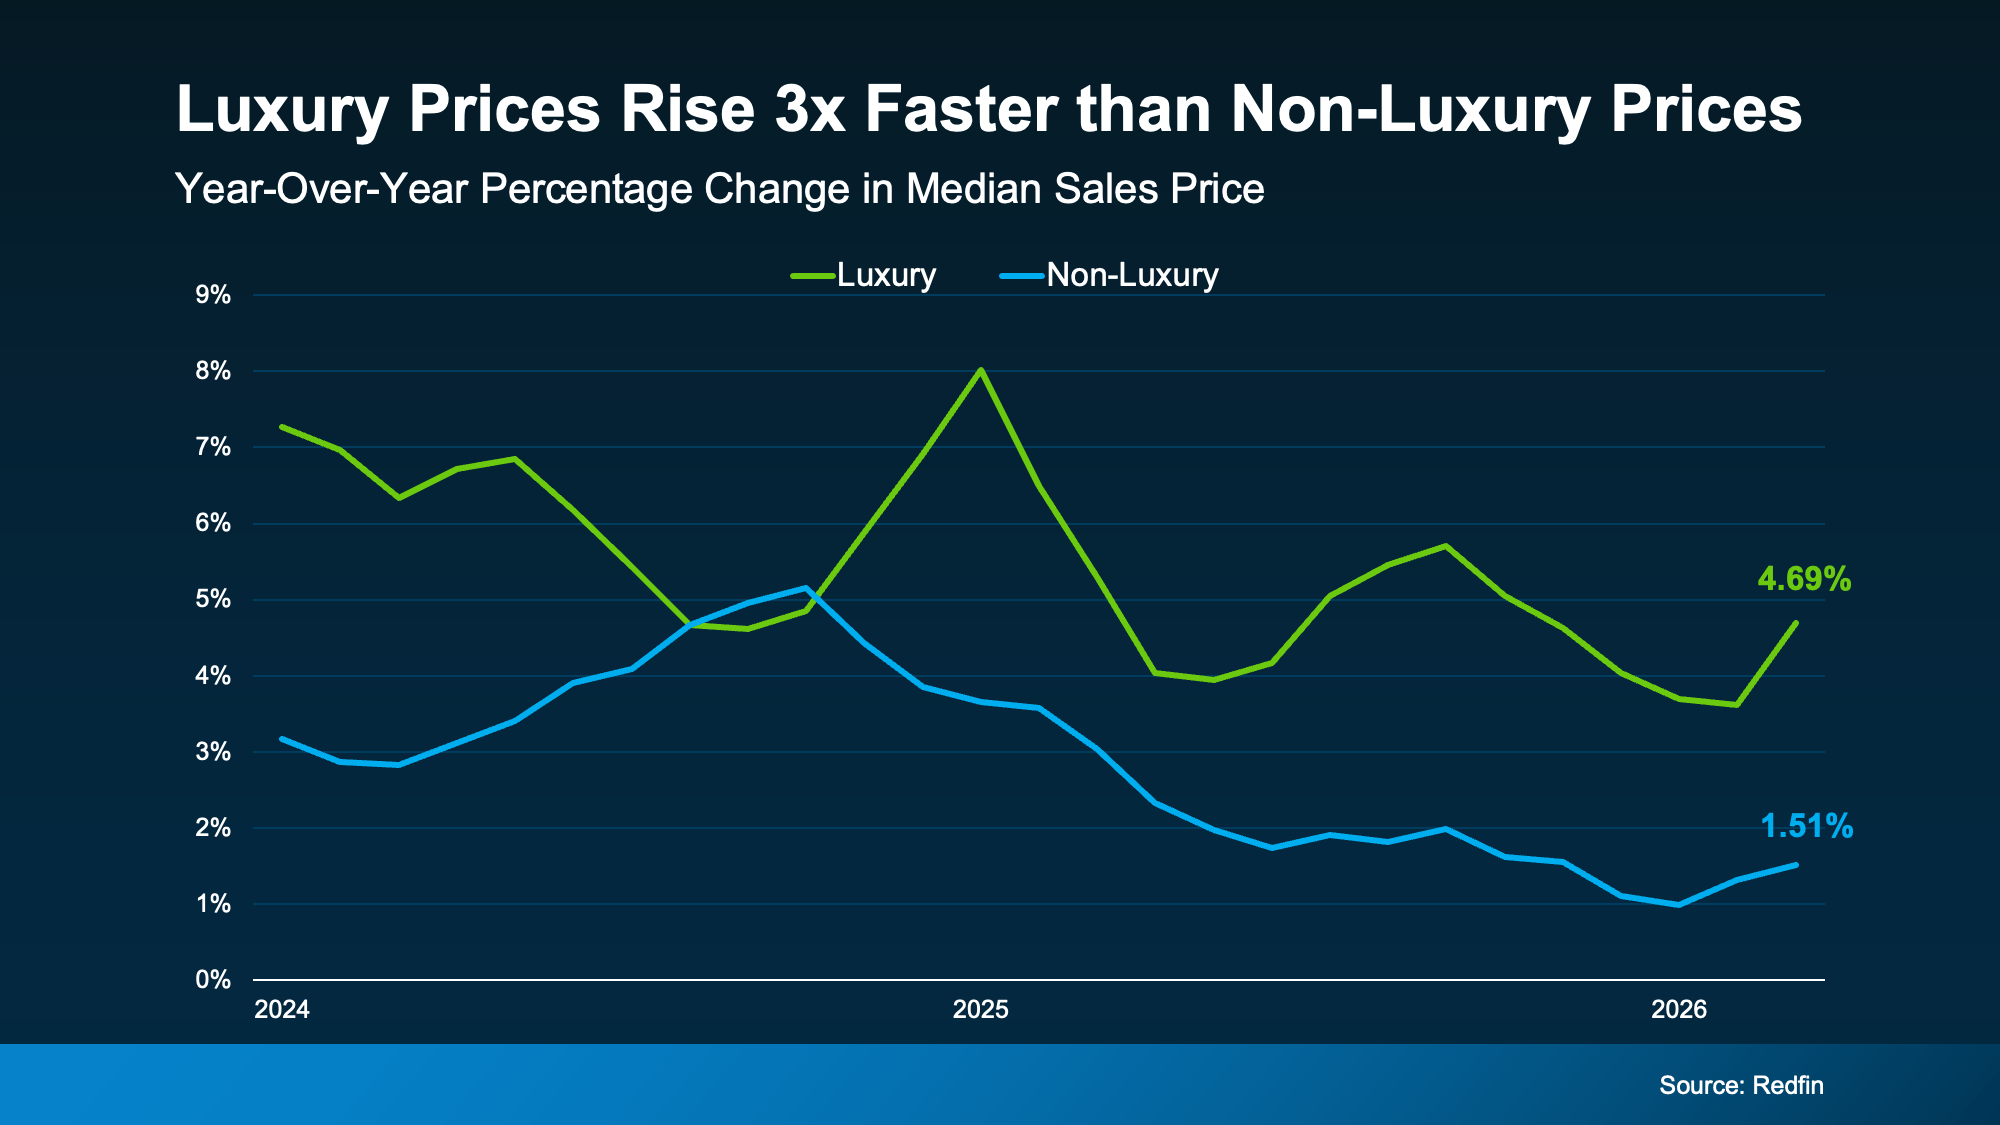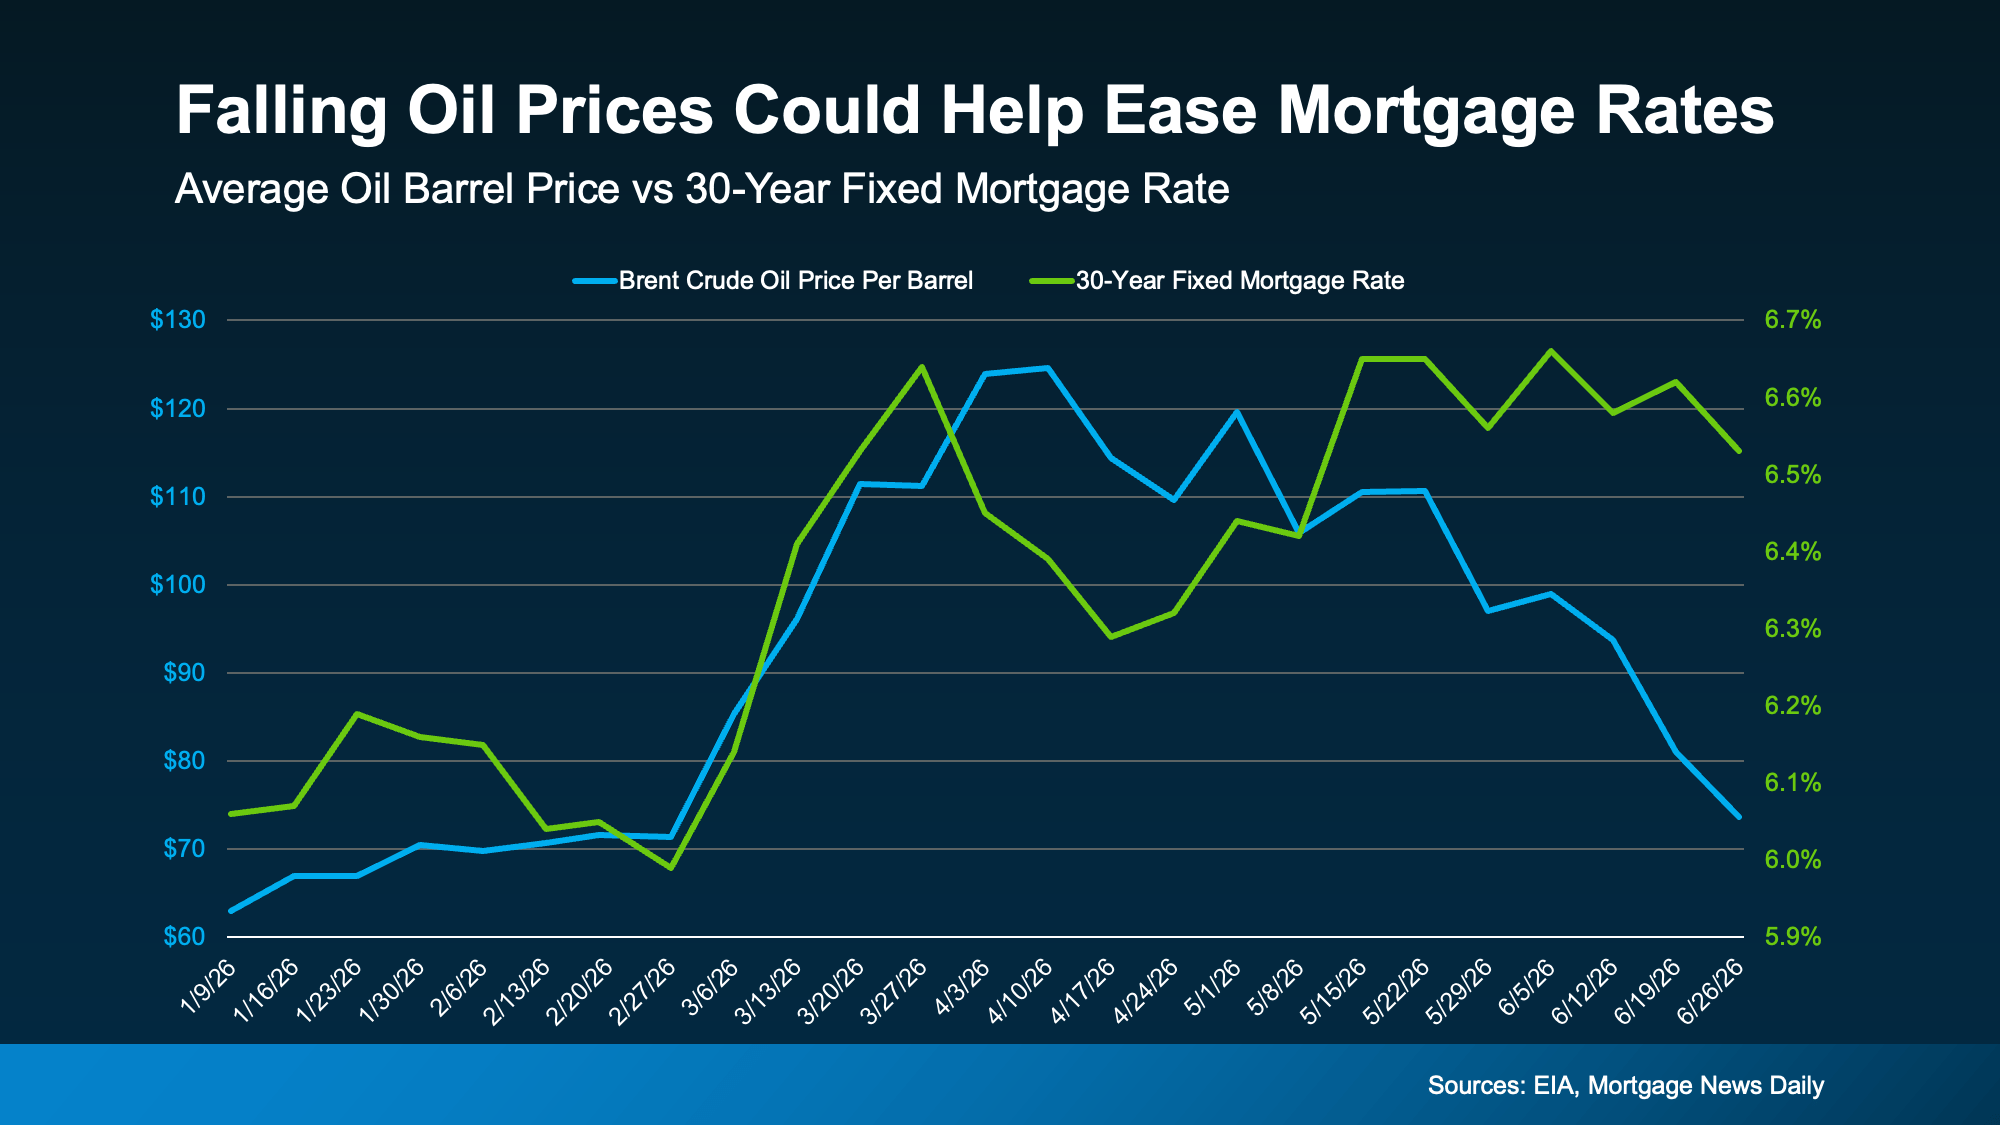
910-279-9398 Download Our Brochure
  • Homes for sale in coastal southeastern NC

Archive for the ‘For Sellers’ Category

Here’s Why Mortgage Rates Are What They Are Right Now

Posted by
Here’s Why Mortgage Rates Are What They Are Right Now Simplifying The Market

If you’re waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there’s a number working behind the scenes that’s actually good for you right now. It’s called the spread, and once you understand it, you may see today’s rates in a whole new light.

The Pattern That’s Held for 50+ Years

For starters, mortgage rates don’t move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.

It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):
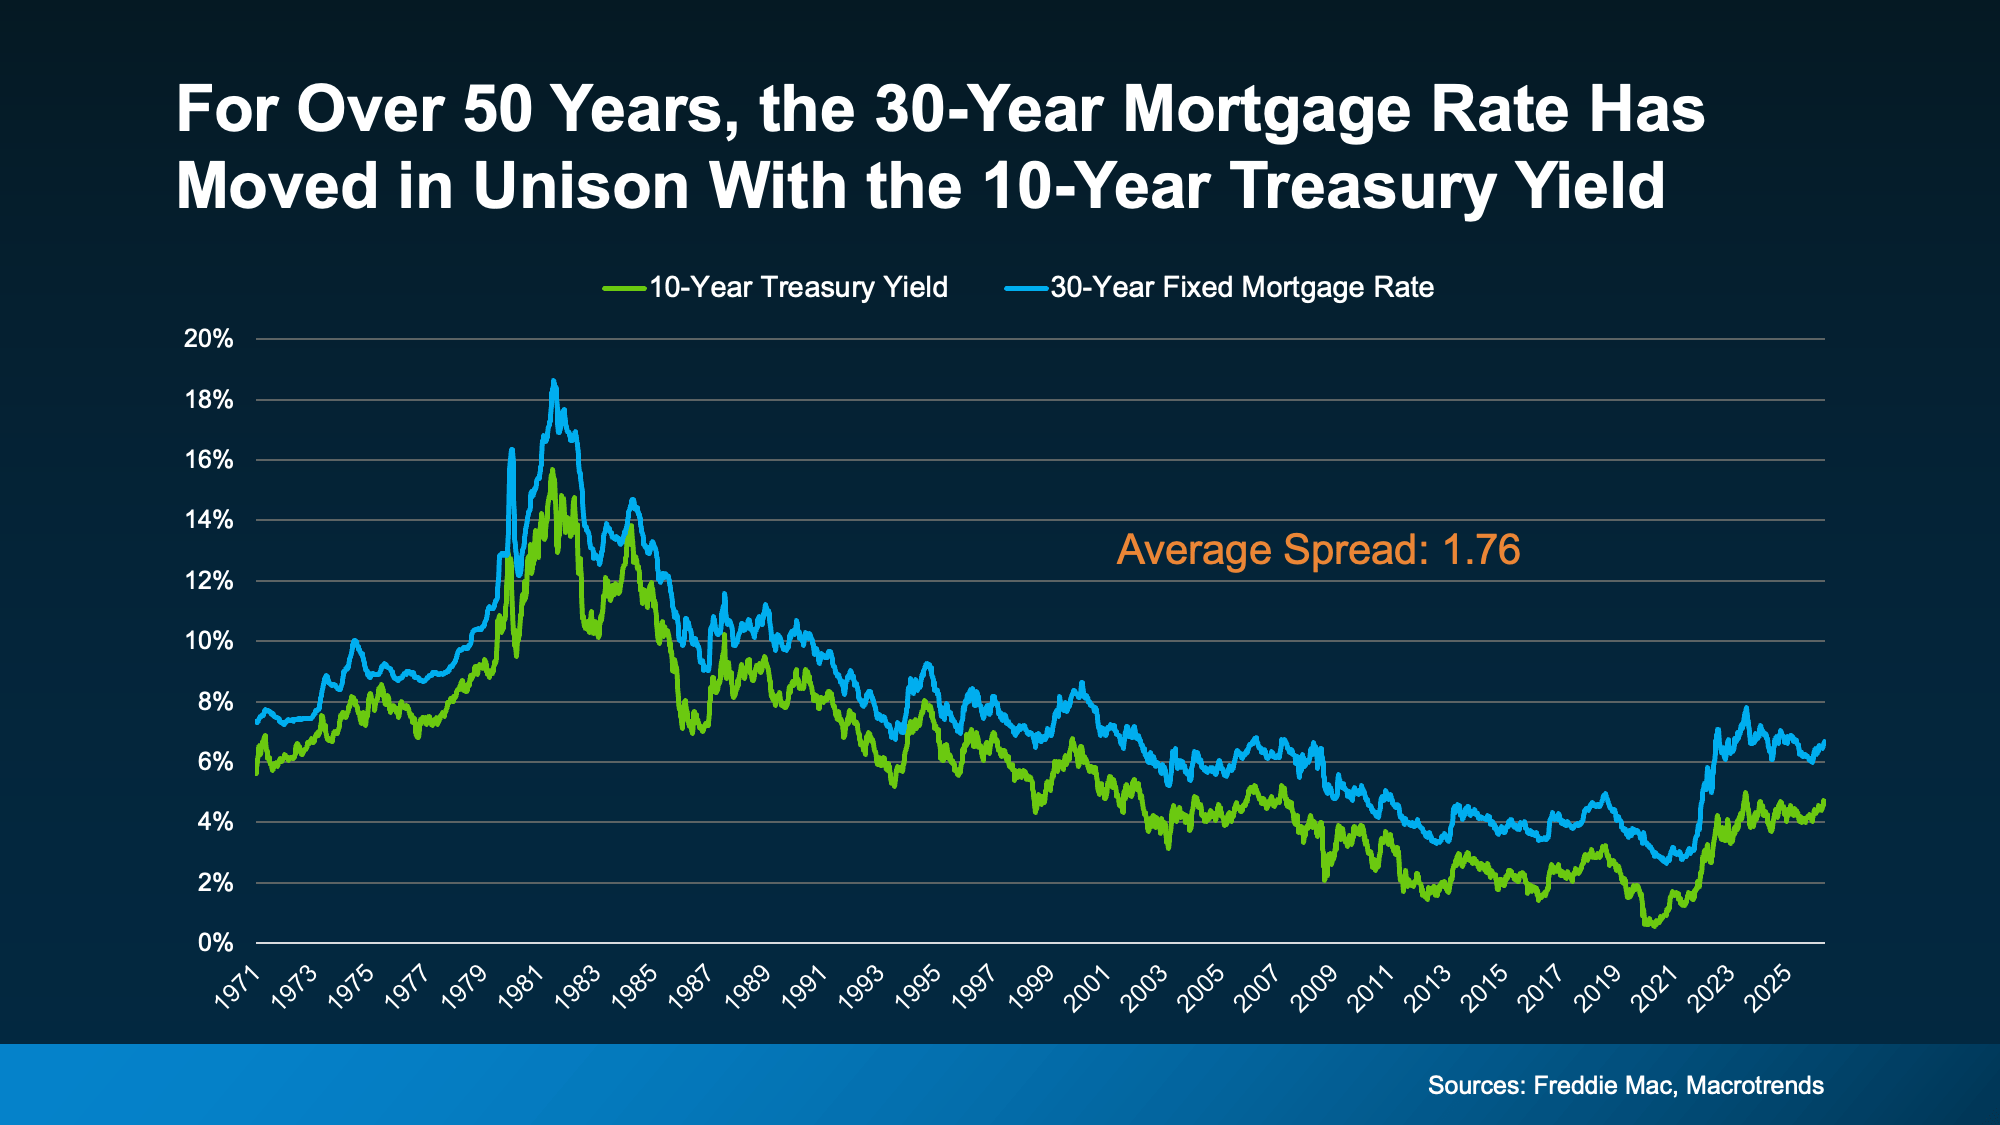
a graph of a graph showing the number of mortgage rates

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.

One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon

If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.

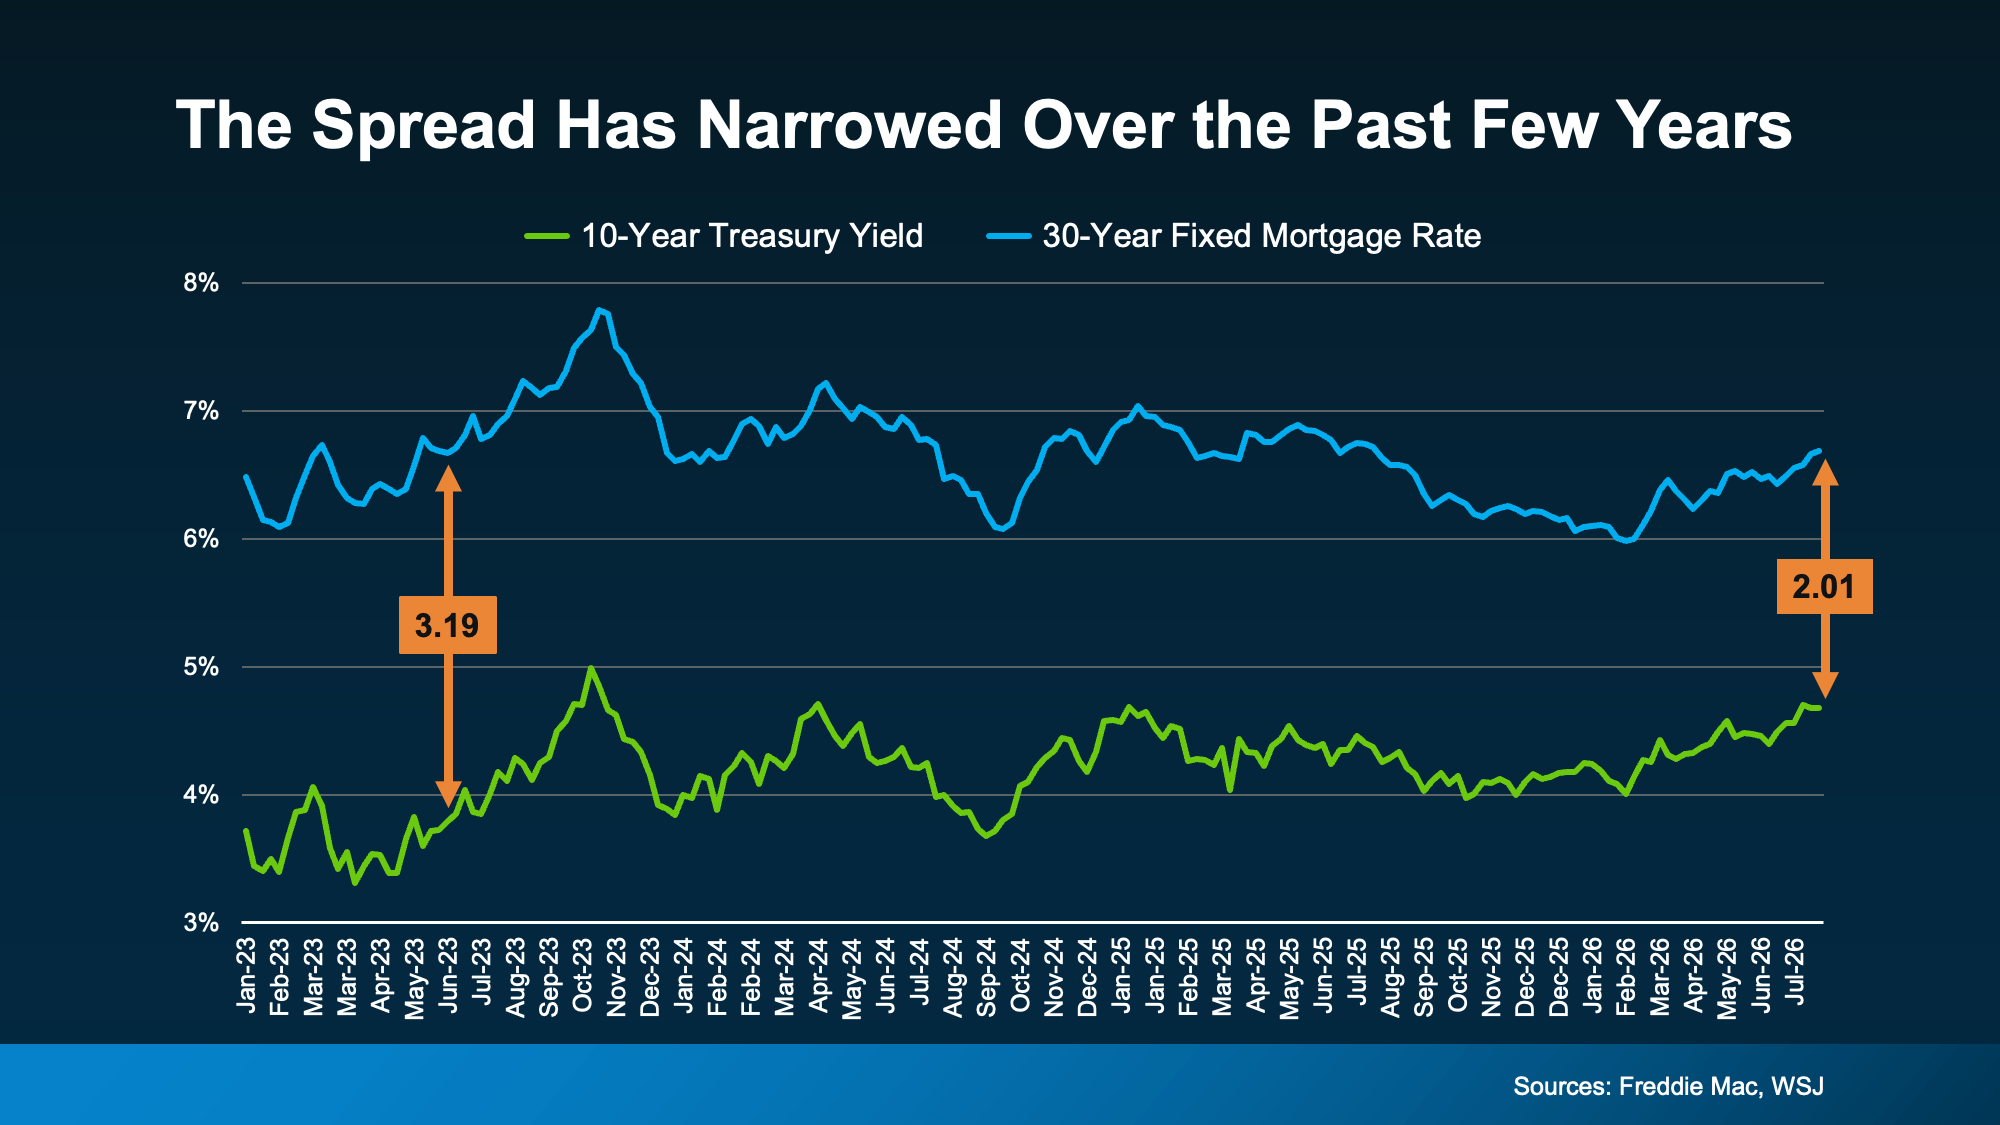
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.

Now here’s the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):
a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.

Why Mortgage Rates Aren’t Higher Right Now

Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today’s 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):
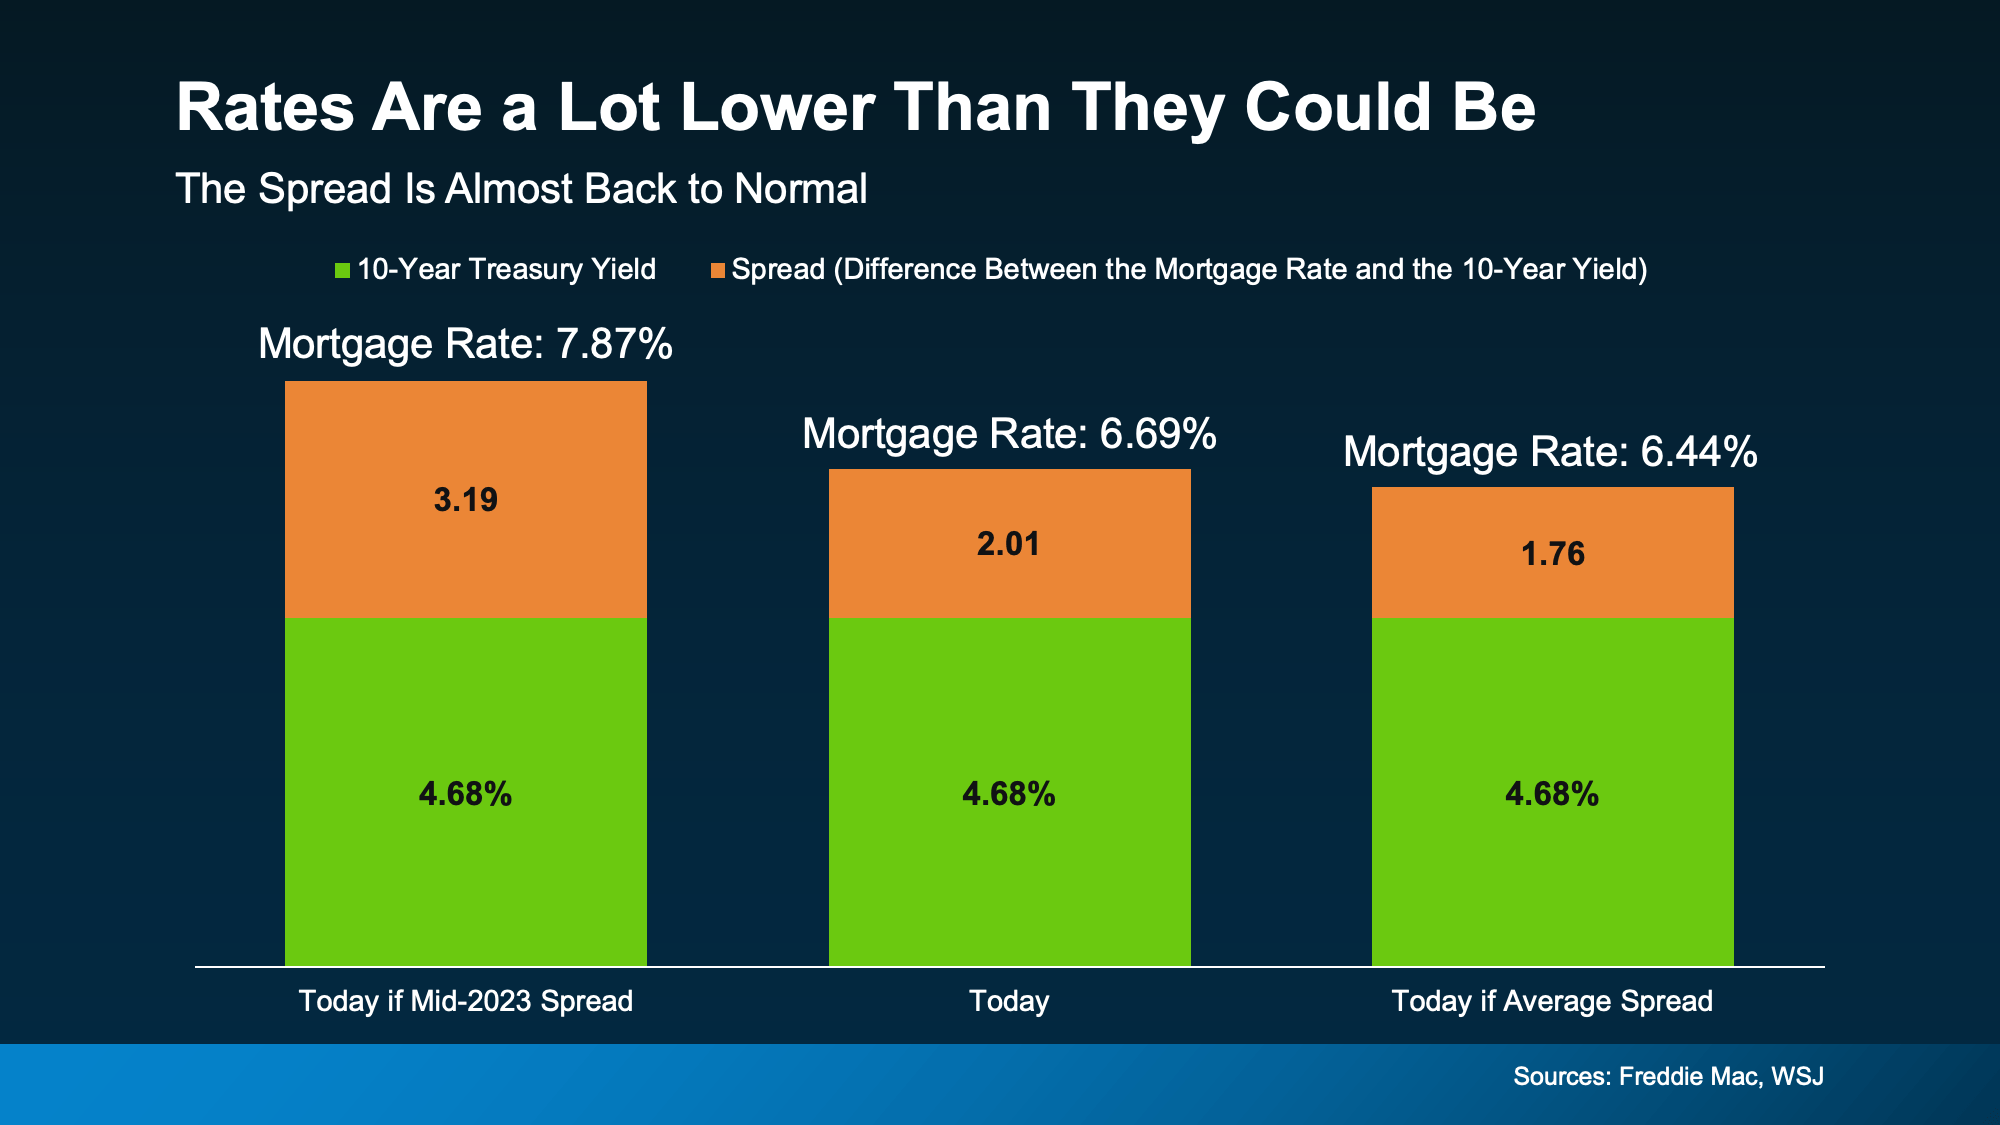
a graph of a graph showing a rate of interest

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.

But now, thanks to the spread narrowing recently, today’s rate sits around 6.69%. That’s the middle scenario in that visual. That’s a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:

“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”

Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That’s only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.

In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.

Bottom Line

That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they’re better than they could’ve been. If you want help figuring out what that means for your monthly payment, reach out to a local lender
Home Price Growth Slowed Down. That May Be Changing.

Posted by
Home Price Growth Slowed Down. That May Be Changing. Simplifying The Market

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you.

The Numbers May Be Starting To Turn

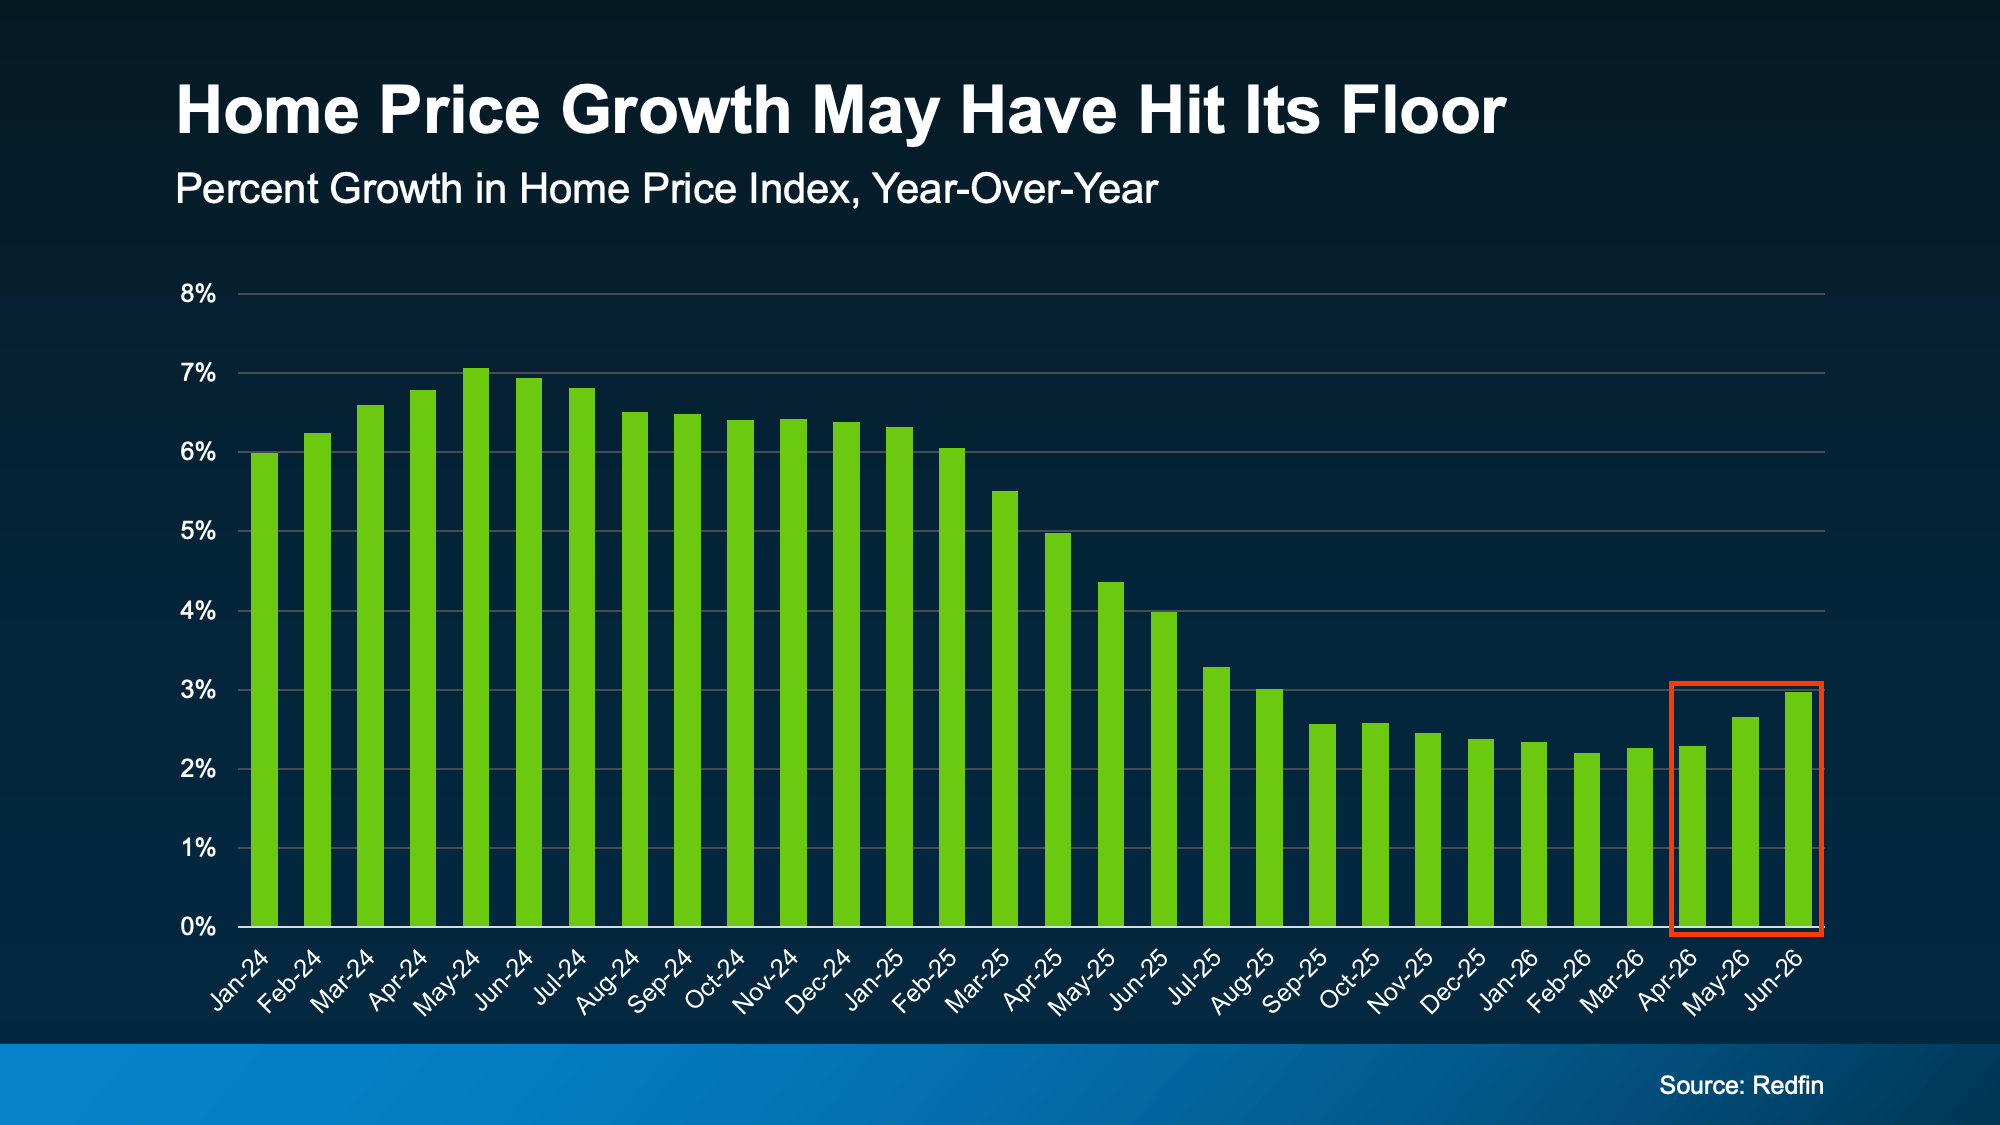
For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.

a graph of growth in a number of years

While a couple months of data doesn’t necessarily mean this will be a lasting trend, there are some other signs that this could continue.

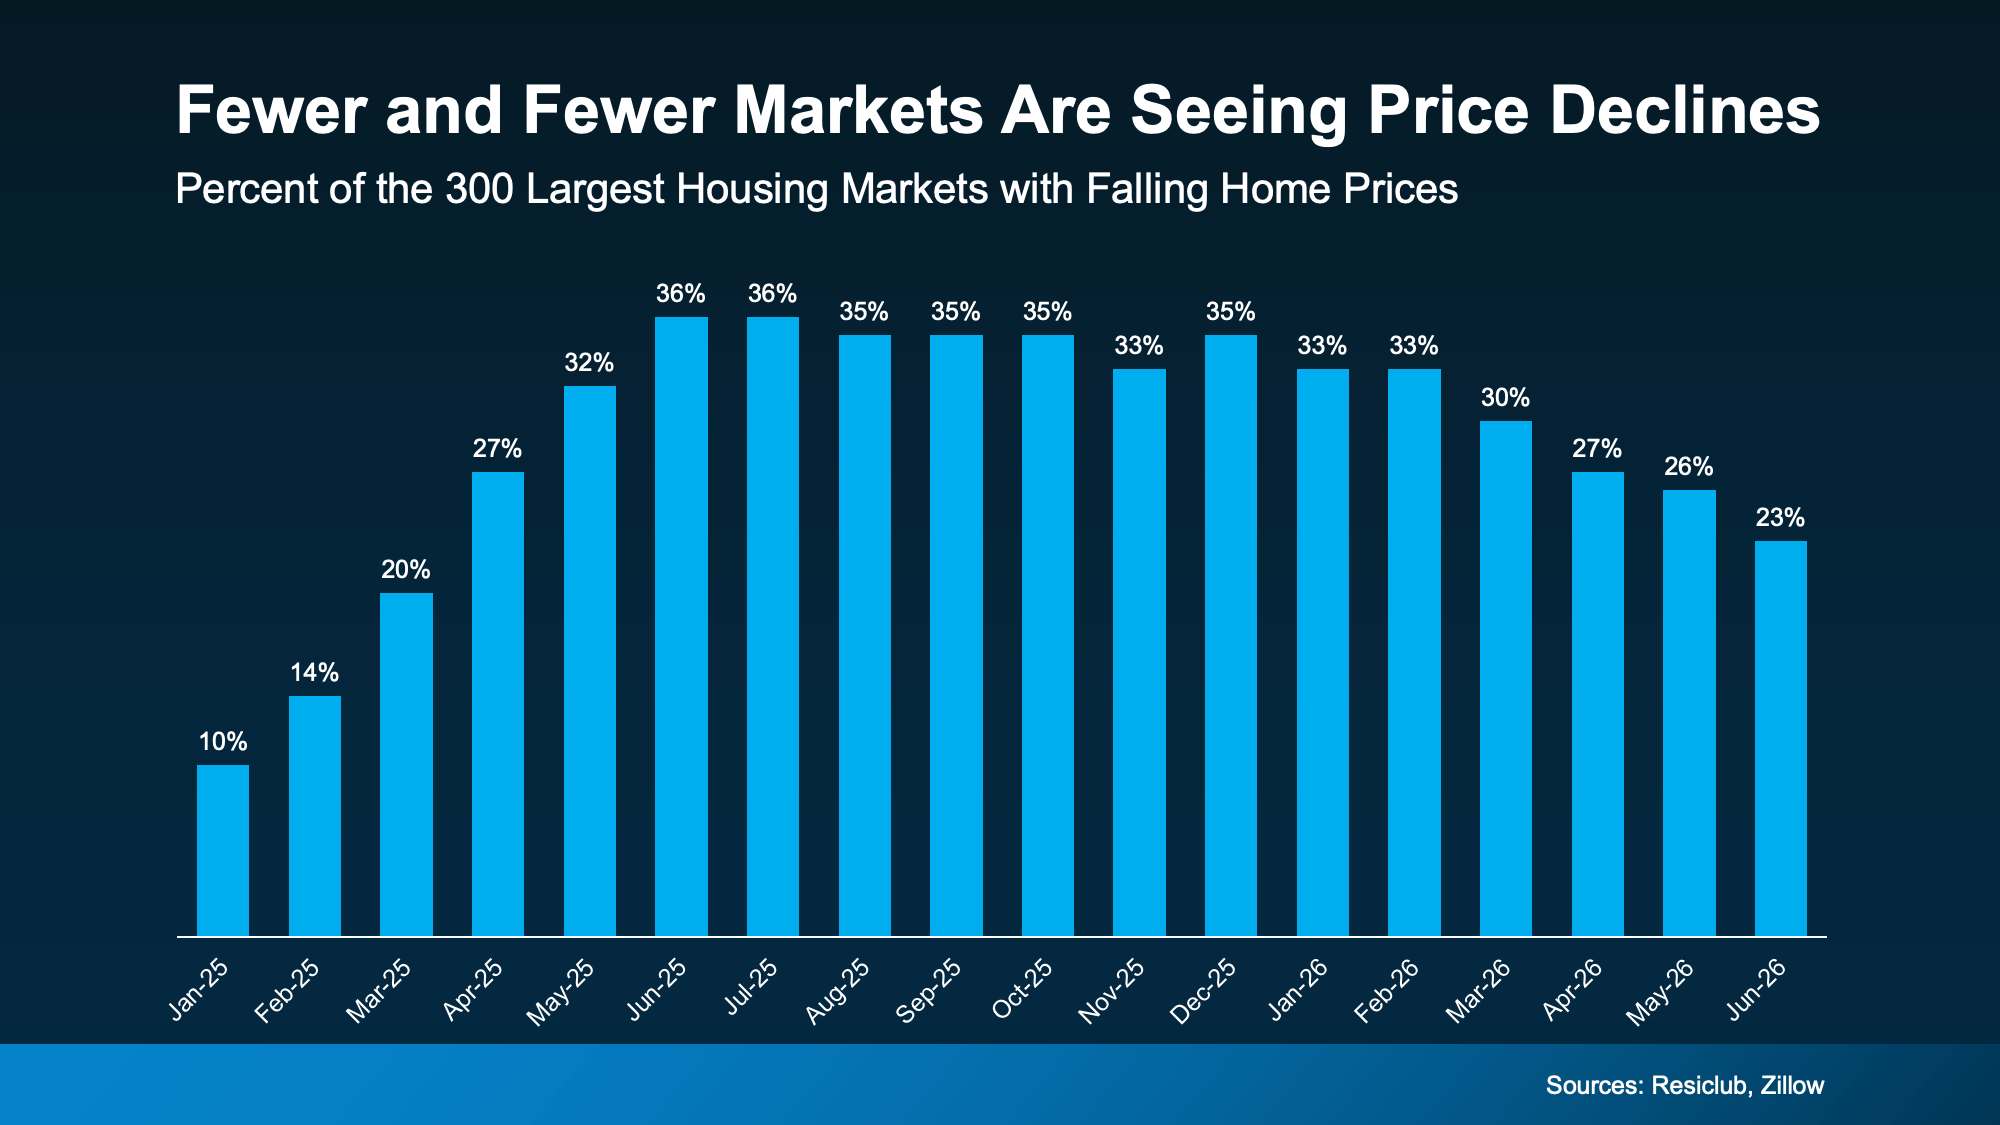
For example, fewer markets are seeing prices decline. According to ResiClub and Zillow, about 36% of the 300 largest housing markets had falling prices as of the middle of last year. Since the start of this year, that share has been shrinking. Now? Only 23% are experiencing those mild dips (see graph below):

a graph of the price of a house

When fewer markets see prices falling, that means more markets are seeing prices rise again.

And forecasts suggest this shift has room to run. On average, experts project home prices will rise about 2.3% nationally this year. And for that to happen, price growth would have to pick up a bit in the second half of 2026.

But Remember, Real Estate Is Local

While it looks like national prices may be starting to pick back up a tiny bit, that doesn’t mean that’s what’s happening in your neighborhood.

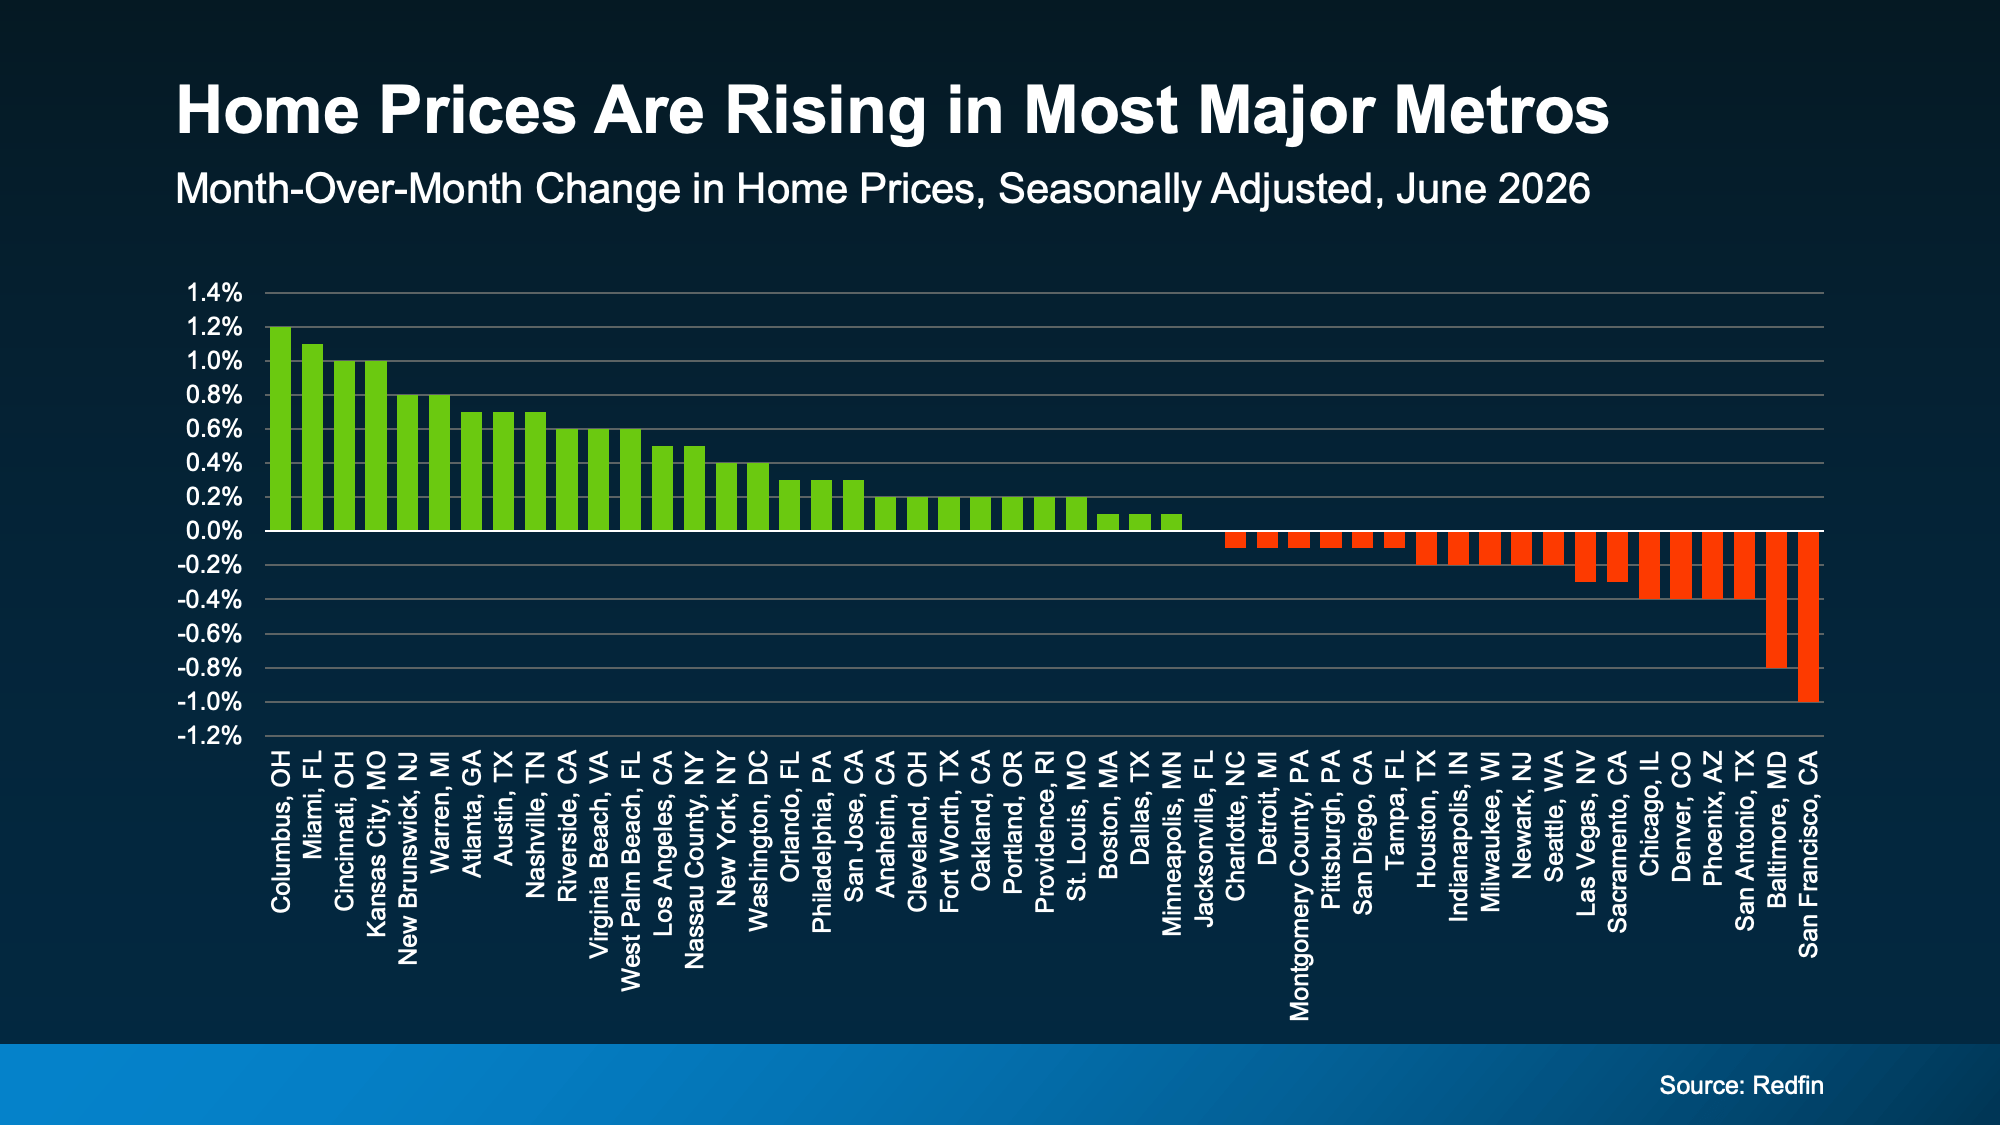
National home prices are really just an average of hundreds of local markets. Some are climbing faster. Others are still cooling. But one reason the national average may be looking up is because a growing number of metros may actually be net positive for prices this year.

Not long ago, the major metros were split about 50/50 – half seeing prices rise and half seeing them fall. Now, that balance looks like it’s starting to tip in a more positive direction. Just last month, more than half of the major metros saw prices go up, according to Redfin (see graph below):

a graph of prices on a dark background

As Selma Hepp, Chief Economist at Cotality, explains:

“. . . local markets continue to tell very different stories. Annual home price growth has changed little since the start of the year, but some markets, especially those supported by strong job and income growth in the West and more affordable Midwest markets, have seen notable acceleration in price gains.”

What This Means for You

Home price headlines can be confusing because they don’t always tell the full picture. Lean on an agent to understand what’s happening in your local market and what the early signs say for where prices may go from here.

That’s the best way to stay one step ahead of the market.

If you’re buying: slower price growth has worked in your favor. You’ve had more room to negotiate and a budget you could plan around. If price growth is picking up in your area, buying now may mean paying less than you would later this year.

If you own a home: you’ve been gaining equity all along, even while growth moderated. If growth keeps picking up, those gains could speed up, too. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), projects the typical homeowner will gain roughly $16,000 in housing wealth this year. And if you’re thinking about selling, this shift is a good early sign for you. Just remember, the market is still pretty balanced and buyer-friendly in a lot of areas right now.

Home price growth slowed way down, and now it’s showing early signs of picking back up. Whether you’re buying or selling, let’s connect so you can see exactly what prices are doing in our local market and what that means for your plans.

Bottom Line

Home price growth slowed way down, and now it’s showing early signs of picking back up. Whether you’re buying or selling, connect with a local real estate agent so you can see exactly what prices are doing in your local market and what that means for your plans.

Selling a Luxury House? Here’s Why Now Is a Good Time

Posted by
Selling a Luxury House? Here’s Why Now Is a Good Time Simplifying The Market

If you own a luxury house, you’re in a stronger spot than most sellers right now. While much of the market has cooled, the high-end tier hasn’t. Sale prices and buyer demand are both up. So if you’re considering selling, now could be a great time to make your move.

Luxury Is Leading on Price

Let’s start with prices. But before we get into it – what actually counts as a luxury home? Generally, these are homes in the top 5% price range for the area, so it varies depending on where you live.

But what’s interesting is that according to the latest data from Redfin, sale prices for luxury houses have risen about three times faster than for non-luxury.

Right now, the typical home’s sale price is up about 1.5% year-over-year. But high-end homes? Their sale prices have gone up nearly 5% since last year (see graph below):

a graph of sales

That’s a bigger deal than it sounds like.

Despite all the talk about slowing price growth lately, sale prices in this segment of the market may be rising faster than you’d expect based on the headlines. That’s going to be a good thing if you’re thinking about selling. And rising sale prices are only half the story.

Buyers Are Showing Up, Too

While so many headlines are talking about how buyers are pulling back, that’s not necessarily true when it comes to luxury homes. In fact, right now, it looks like the higher the price point, the more active the buyers.

Lawrence Yun, Chief Economist with the National Association of Realtors (NAR), explains:

The luxury market has really performed better compared to the lower price point. . . . if we look at price points, any home priced under $250,000, virtually no change in unit sales from one year ago. Then you go into the upper price category, and home sales are up about 10% from one year ago. But the million dollar-plus homes, it is up by 18% from one year ago.

Basically, more homes are selling on the upper end of the market. A big reason is that high-end buyers tend to feel less of the affordability pressure weighing on many households today, so they keep buying even when the wider market slows.

That demand also means that luxury houses don’t stay on the market as long as they used to.

Luxury Houses Are Selling Relatively Quickly

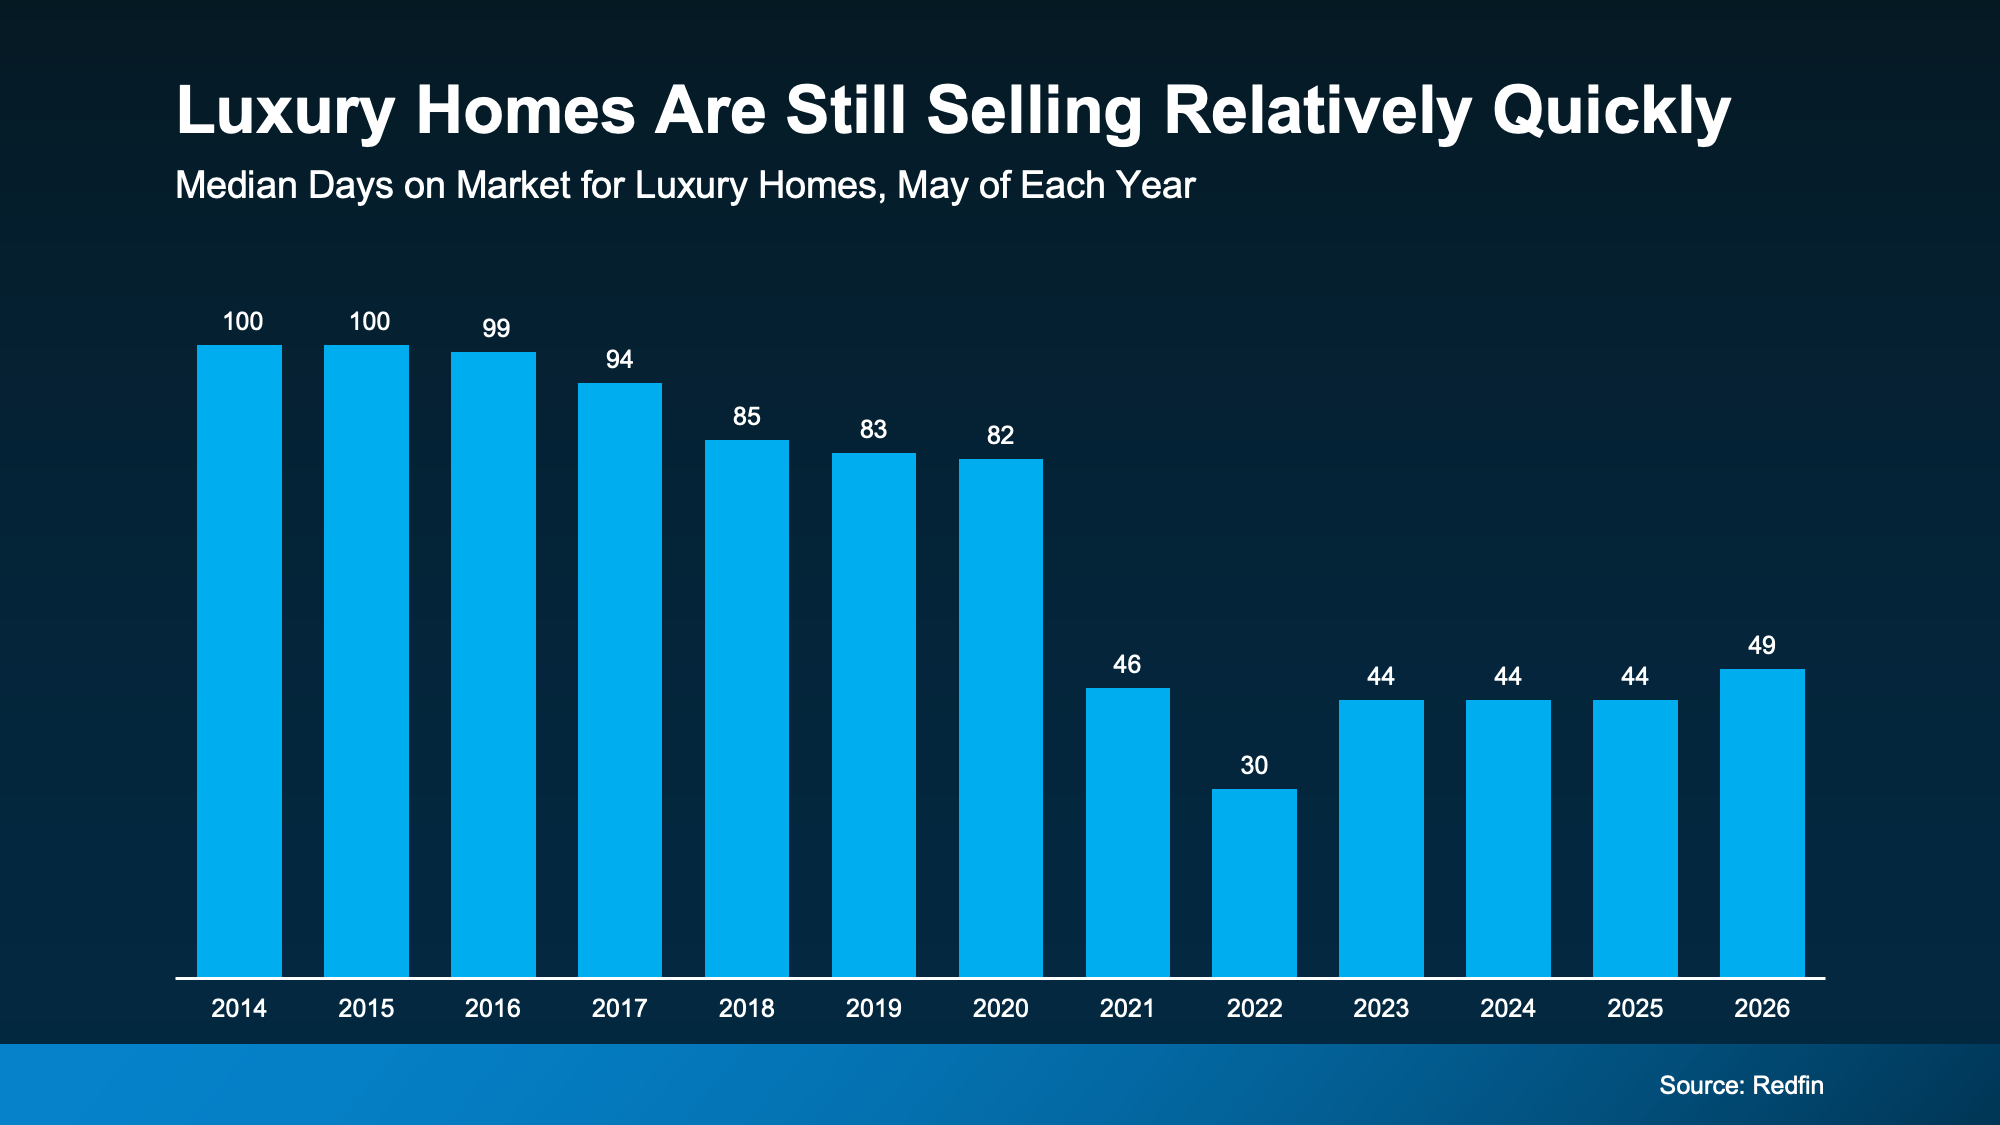
According to the most recent data from Redfin, for luxury homes the median number of days on market is under 50. That’s much faster than pre-pandemic norms going even as far back as 2014 (see graph below):

a graph of sales in a market

That means you probably won’t spend a ton of time sitting in limbo wondering when you’ll get an offer.

Bottom Line

Selling a high-end house is a big decision, and you deserve to feel confident going in. With sale prices climbing and buyers active at the top, this is a strong window to make your move.

When you’re ready to cash in, connect with a local real estate agent to talk strategy.

The House That Started It All Could Kickstart What’s Next

Posted by
The House That Started It All Could Kickstart What's Next Simplifying The Market

Remember how exciting it was to buy your first place? It felt like crossing a long-awaited finish line. It gave you a place to build your life. Maybe it’s where you lived when you got married. Or where you welcomed a child or a pet into the family.

But that was just the beginning.

For most people, your first house was never meant to be your forever home. It’s a stepping stone for what comes next.

And if your life looks different today than it did when you got the keys, you’re not stuck. Moving may be more realistic than you think.

Starter Home Inventory Is Still Relatively Low

If you’ve been wondering whether now is the right time to move up, here’s something worth knowing. Starter homes remain one of the hardest types of homes to find. And that’s good news if you’re thinking about selling your first place.

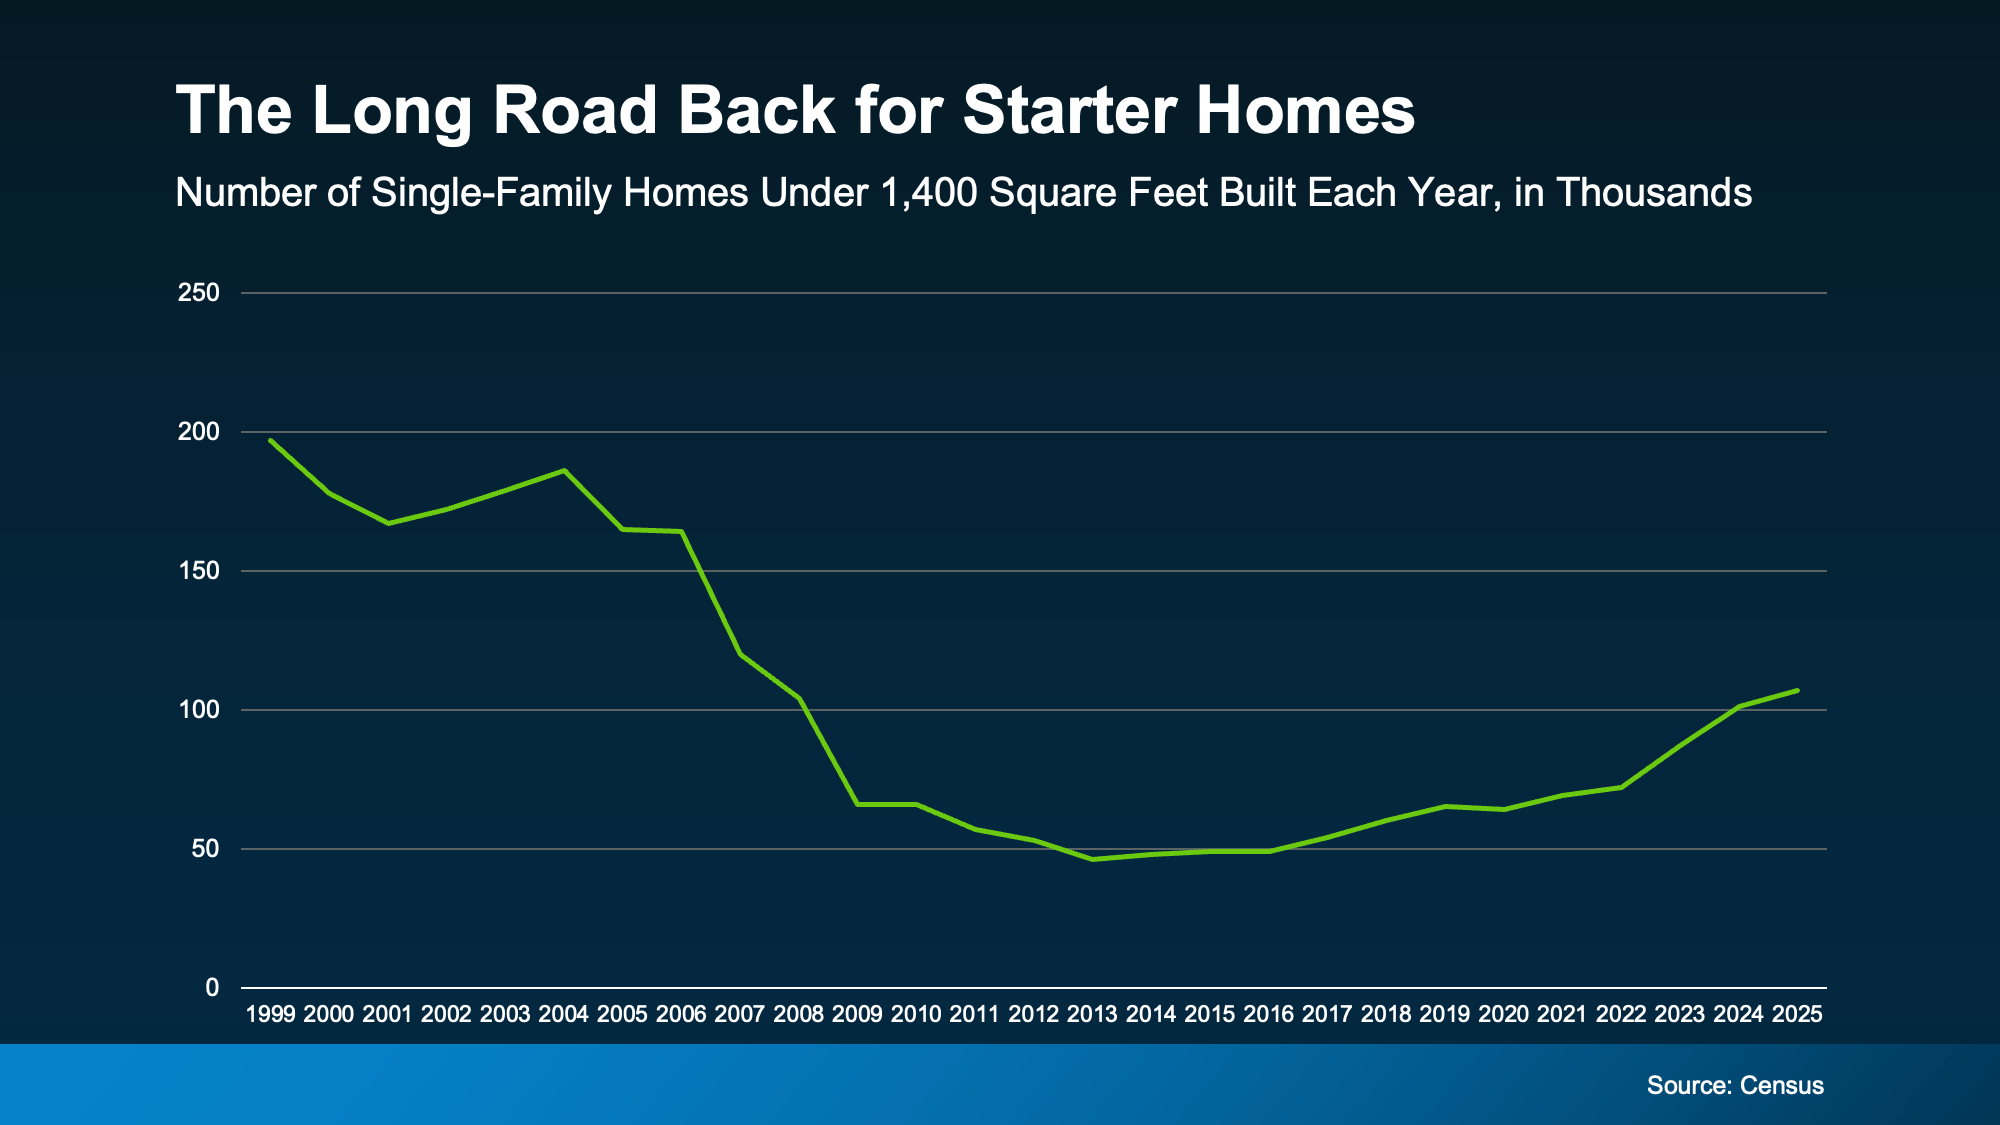
Historically, we haven’t been building enough homes for first-time buyers. And even though homebuilders have shifted more attention toward smaller, entry-level homes lately, the Census shows there’s a long way to go to re-build supply (see graph below):

a graph showing a growing trend

That means your current house is in demand – and that’s a dream scenario for sellers. But that’s only half the story. You also need somewhere to go.

There Are More Move-Up Homes on the Market

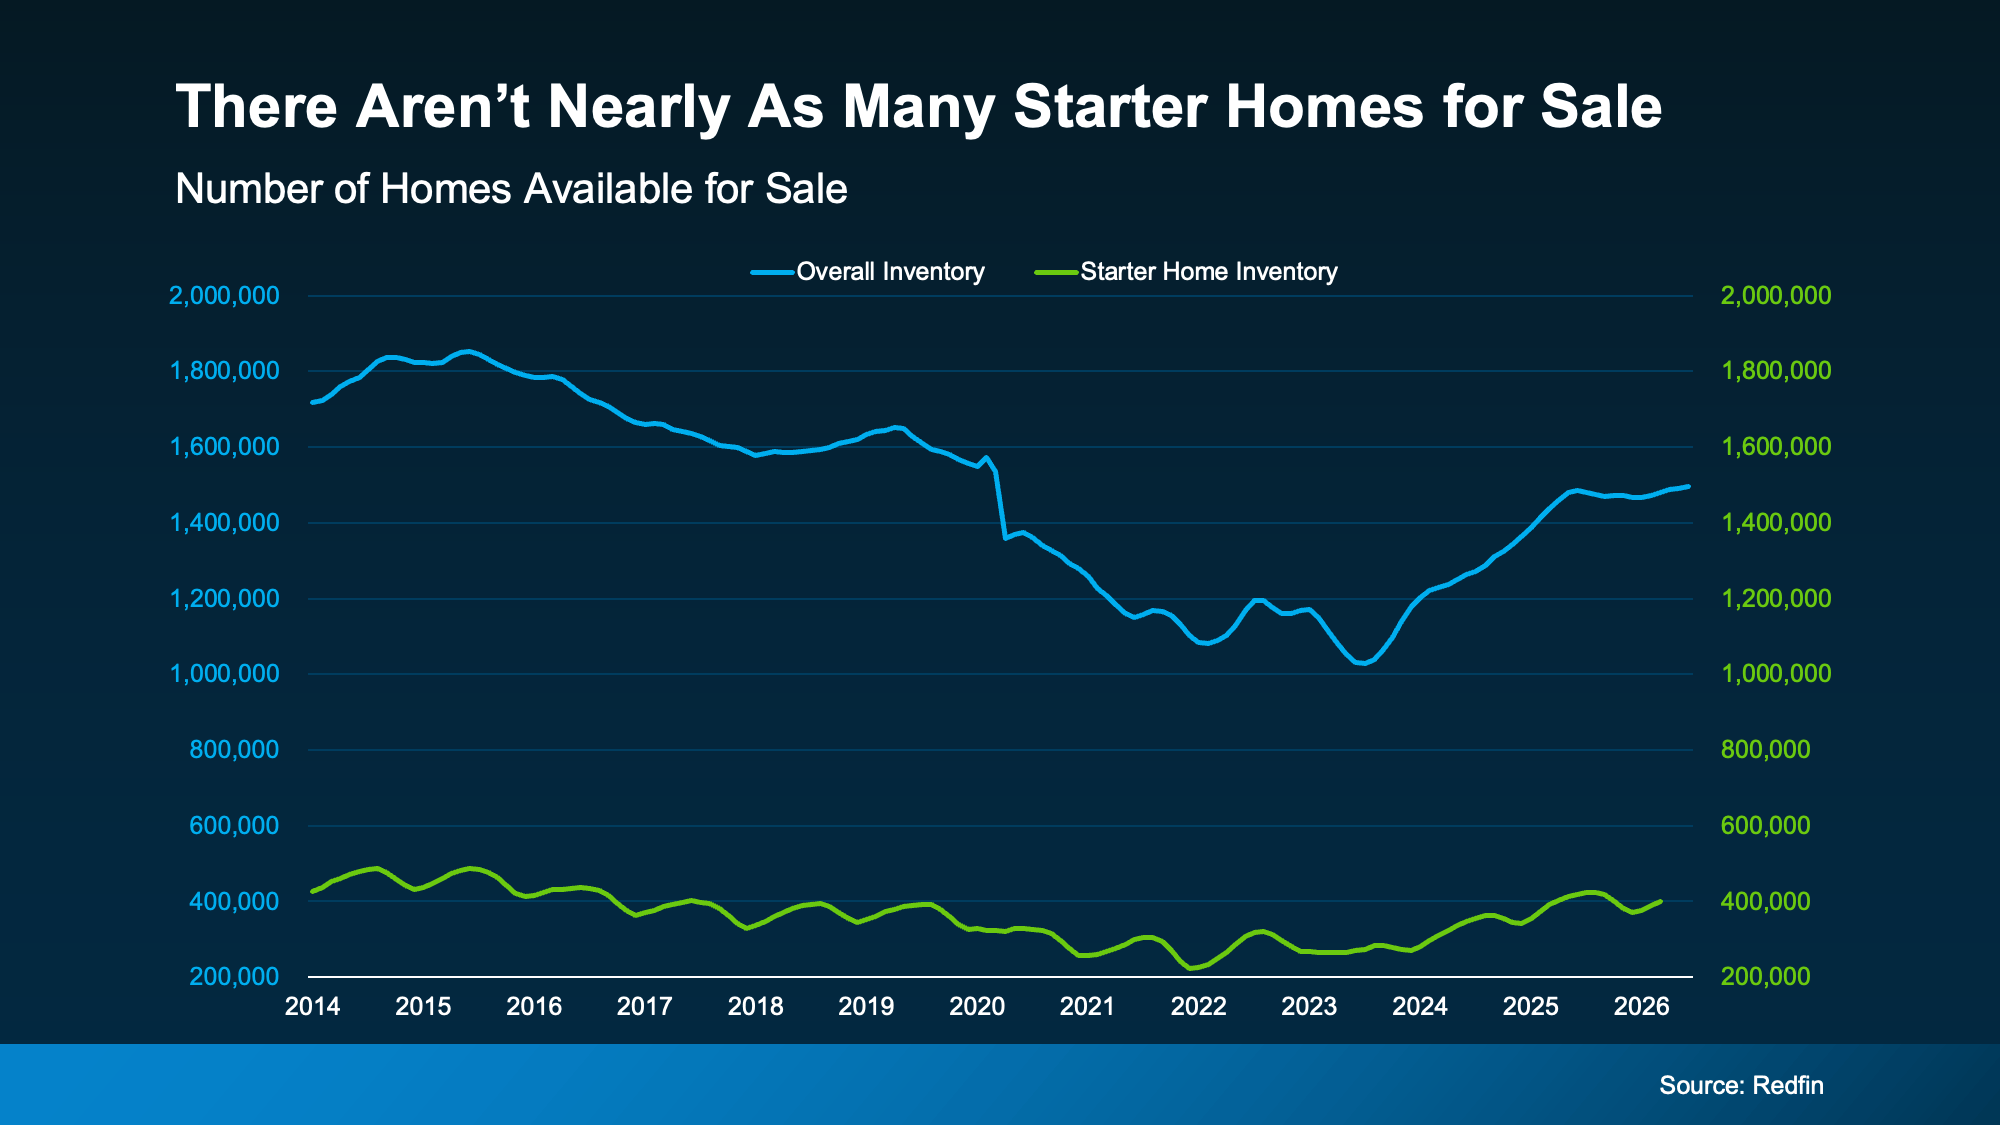
Here’s where this gets interesting. While the supply of starter homes remains tight (the green line), data from Redfin shows that the number of homes for sale has been climbing overall (the blue line):

a graph of sales and prices

As Nadia Evangelou, Principal Economist and Director of Real Estate Research at the National Association of Realtors (NAR), explains:

“Too much of the inventory available today remains concentrated at higher price points, leaving a shortage of options for entry-level and middle-income buyers.”

That means you may have more choices for your move up than you’d expect. Whether you’re hoping for another bedroom, a home office, a bigger backyard, or simply more room for this next stage of life, today’s market may finally be giving you the chance to find it.

At the same time, your current house may be exactly what someone else has been looking for because homes like yours are still in short supply. That’s a unique advantage for move-up buyers. And it could help you sell for a stronger price. As Zillow says:

“Starter home value appreciation has outpaced other types of homes nationally, mostly because they’re so in demand.”

Your Biggest Advantage May Be Your Equity

Here’s the cherry on top. There’s one more thing your first home has been doing behind the scenes, and that’s building equity. Every mortgage payment you’ve made and every year your home’s value has grown has quietly increased your ownership stake in your house.

According to Cotality, the average homeowner with a mortgage has $295k in equity built up. While your number may be different, once you sell, it could become the down payment on your next home or help reduce the amount you need to borrow at today’s rates.

Put it all together and your move up becomes a lot more realistic than you think:

  • The house you’re selling is in demand.

  • The house you’re buying may be easier to find.

  • And the equity you’ve built can help bridge the gap between the two.

Your first home did exactly what it was supposed to do. It gave you a place to start.

Now, it may be the thing that helps you take the next step.

Bottom Line

Your first home was never meant to be your forever home. It was meant to help you build a life and build the financial foundation for whatever came next.

If your current home no longer fits the life you’re living today, connect with an agent. You may be closer to your next chapter than you realize.

Think Nobody’s Buying Homes Right Now? Think Again.

Posted by
Think Nobody's Buying Homes Right Now? Think Again. Simplifying The Market

If you’ve been thinking about selling, you’ve probably seen plenty of headlines suggesting buyers have just about disappeared. But there’s a big difference between a slow market and a stalled one.

Yes, mortgage rates are still higher than most people would like. Homes aren’t selling as fast as they were. And every week seems to bring another headline about buyers sitting on the sidelines. But here’s what you haven’t heard.

Despite everything going on, buyer demand has been remarkably resilient.

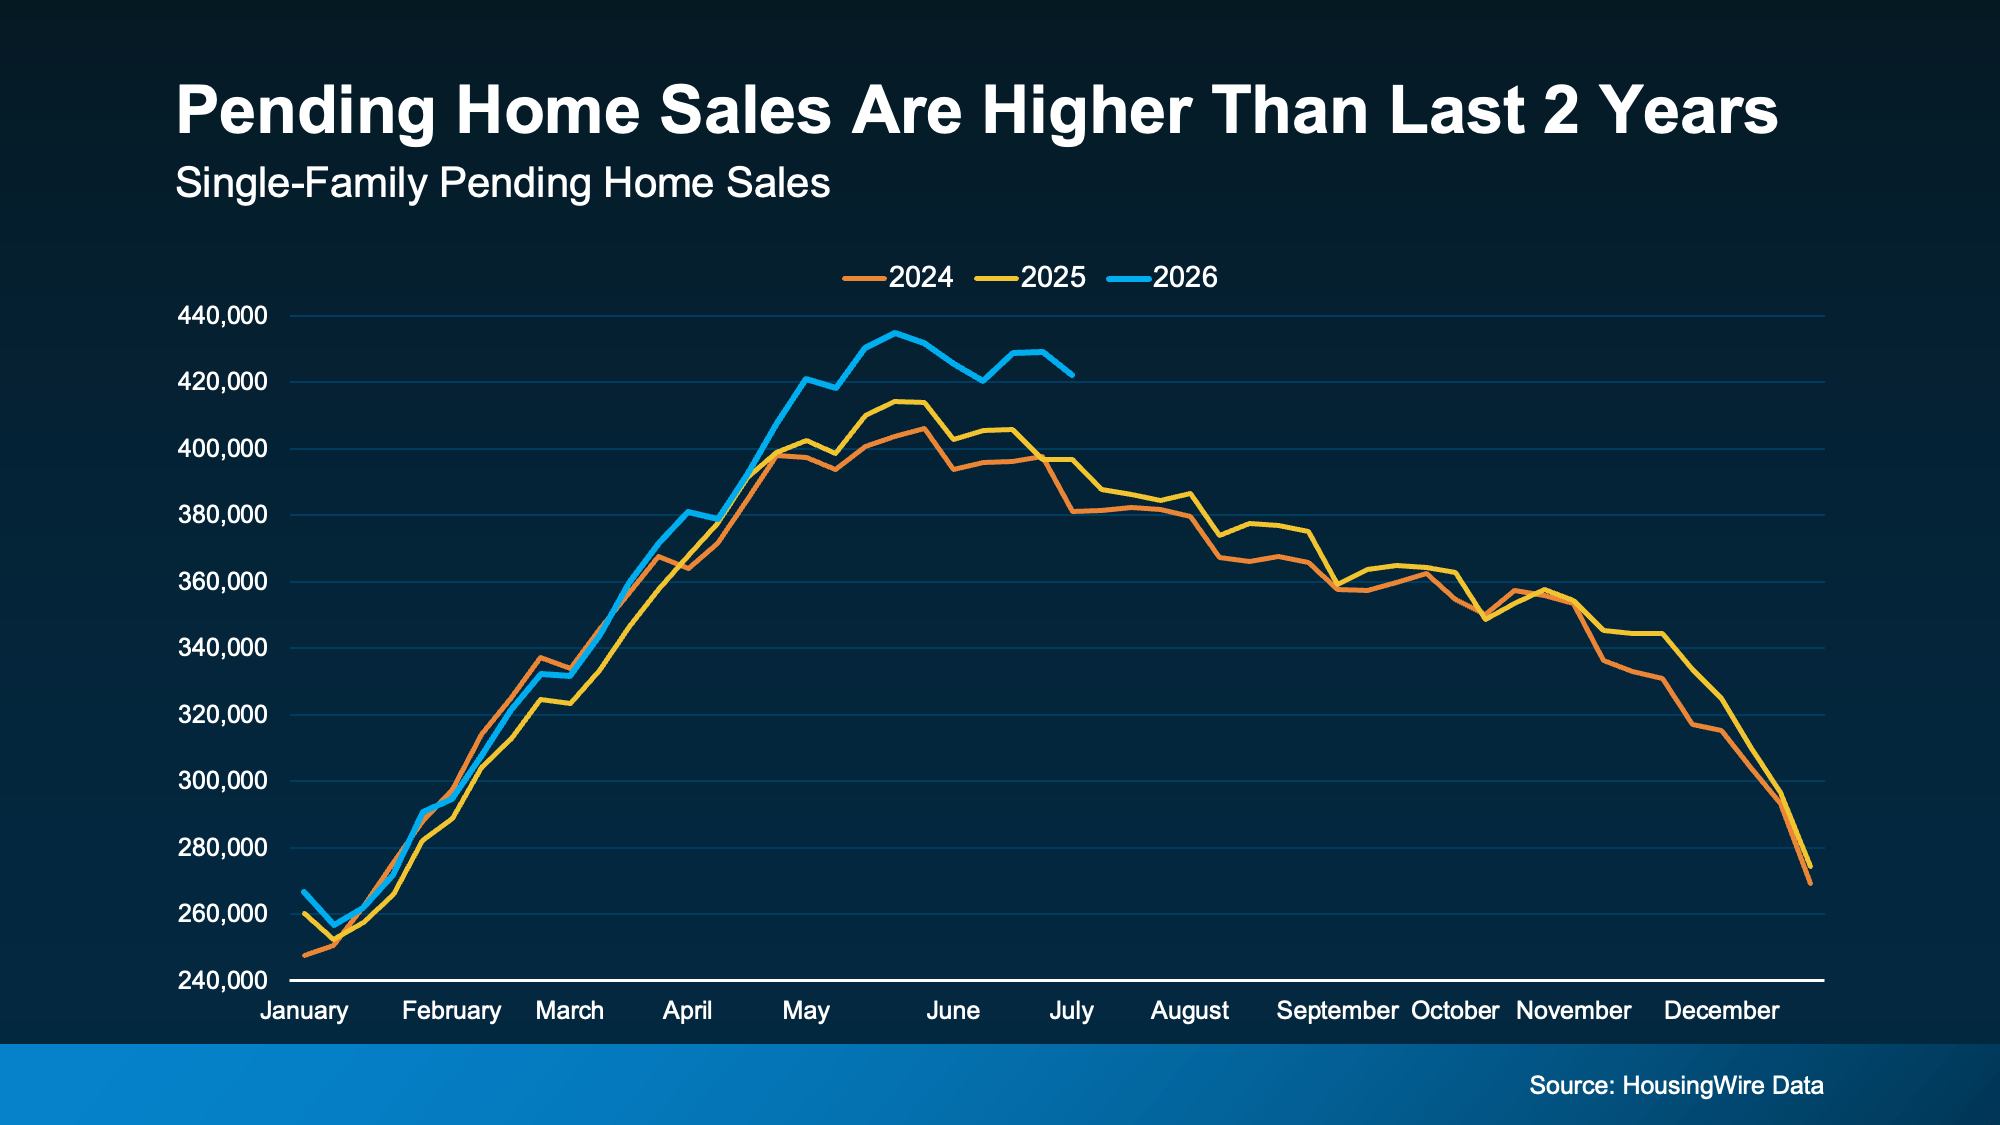
In fact, more sellers are getting to put up the “pending sale” sign now than during the last two years. What’s even more surprising is that they’re doing it at a time of year when activity usually starts to slow down.

And if you’re thinking about selling, that’s a trend worth paying attention to.

Buyers Are More Active Than You Think

One of the best ways to measure buyer demand is by looking at pending home sales. Those are homes that have gone under contract but haven’t closed yet. Think of them as a real-time pulse check on the market and whether buyers are still buying.

HousingWire Data shows more homes are going under contract than at the same time the past 2 years (see graph below):

a graph showing the sales of a home sales

While it may come as a surprise, the numbers speak for themselves. It doesn’t mean buyers are everywhere, but it does mean they’re still active right now. And even if this ebbs and flows a bit in the weeks ahead, right now we’re still ahead of where we’ve been lately. That’s encouraging news if you’re thinking about selling because it tells us something important…

People haven’t stopped buying homes. Serious buyers are still making moves.

And a lot of these people are buying because they decided they can’t keep waiting. Whether it’s a growing family, a new job, retirement, or simply wanting a different home, life keeps moving… even when mortgage rates stay higher than we’d like. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:

“A late spring buyer rush—even with mortgage rates not budging—is an indication of pent-up housing demand and consumers’ acceptance of above-6% mortgage rates as the new normal.”

So, if you’ve been worried no one’s buying, this data should give you some confidence. Today’s buyers aren’t just casually browsing open houses on a Sunday afternoon, they’ve spent months waiting for rates to improve and now they realize they can’t wait anymore.

That means they have a purposeand a timeline. And that’s exactly the kind of motivated buyer you want to work with.

What This Means for Your Sale

Does that mean every house will sell instantly? No.

Today’s market is more balanced than it was a few years ago.  So, you can’t just price your house however you want or skip preparing it for the market.

Now buyers have choices, and they’re willing to wait for the right home at the right price. But sellers who understand today’s market (and price and position their homes right) are still finding success. Because the idea that “no one’s buying right now” just isn’t supported by the data.

The buyers are there.

The opportunity is there.

The key is having the right strategy to capture it.

Bottom Line

This year’s housing market may be moving slower than many of us hoped. But, buyer demand is more resilient than the headlines suggest.

If you’re wondering whether there are enough buyers for your house, connect with a local agent. They can show you what’s happening in your local market and build a strategy that helps you take advantage of the momentum that’s already here.

The “Take It or Leave It” Attitude Is Fading from the Market – What That Means for You

Posted by
The “Take It or Leave It” Attitude Is Fading from the Market – What That Means for You Simplifying The Market

Negotiations are back. More buyers are asking for better deals, and more sellers are giving them. Builders are throwing in extras, too. 

That’s why whether you’re buying or selling today, there are two terms you’ll hear a lot: concession and incentive.

  • A concession is something a seller agrees to during negotiations to get a deal done.

  • An incentive is a perk a builder (or a seller) advertises upfront to attract buyers.

Let’s run through what you need to know about both and how they could play a role in your move.

More Sellers Are Agreeing to Concessions

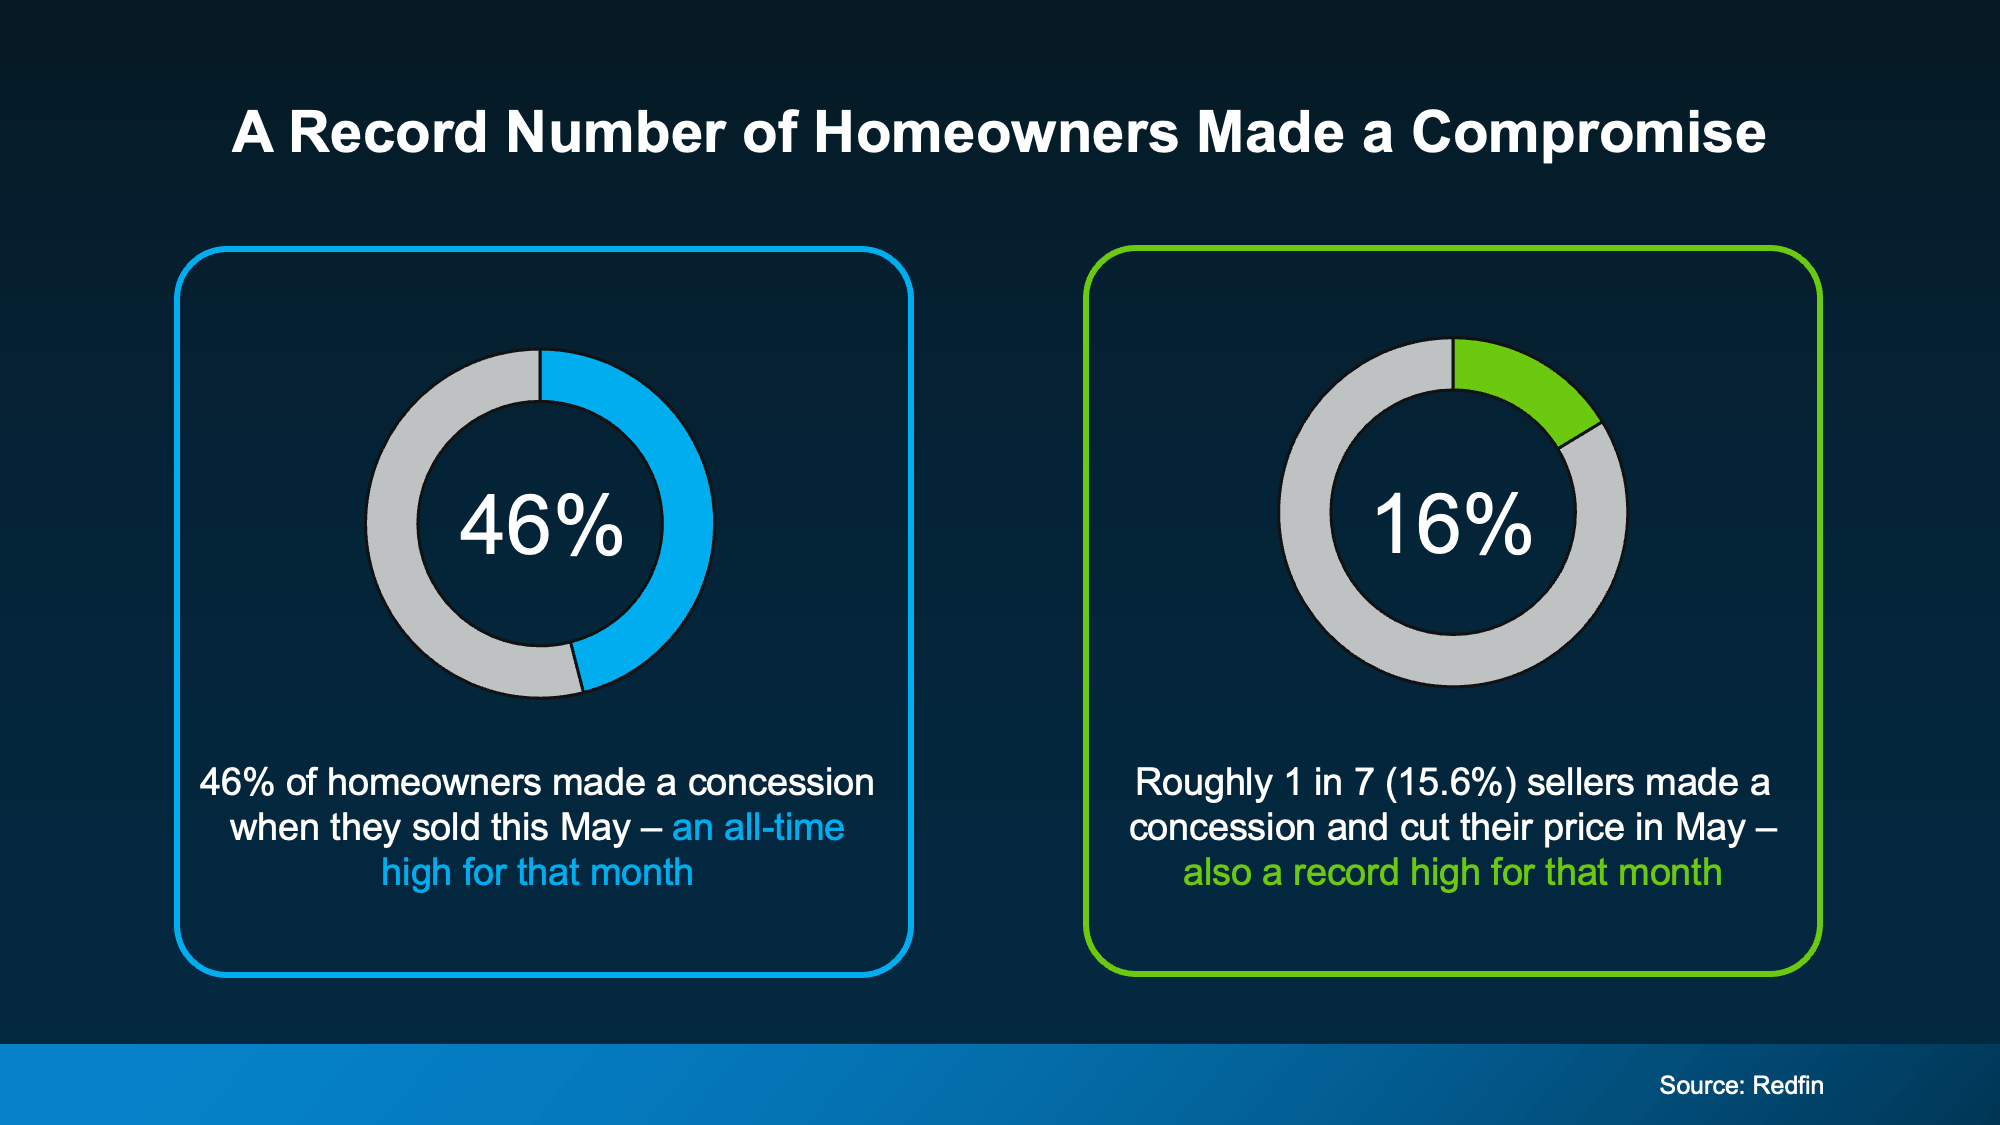
Almost half (46%) of homeowners who sold recently gave the buyer a concession, according to Redfin. That’s the highest share on record for this time of year. And roughly 1 in 7 (16%) sellers went a step further, cutting their asking price and offering a concession on top (see chart below):

a diagram of a homeowner's market 

So, what kind of concessions are we talking about?

A seller might cover part of your closing costs, take care of a repair, or offer a credit that trims your upfront costs. It’s how they keep a deal on track when buyers have more options to choose from – and homeowners aren’t the only ones compromising.

Builders Are Cutting Prices, Too

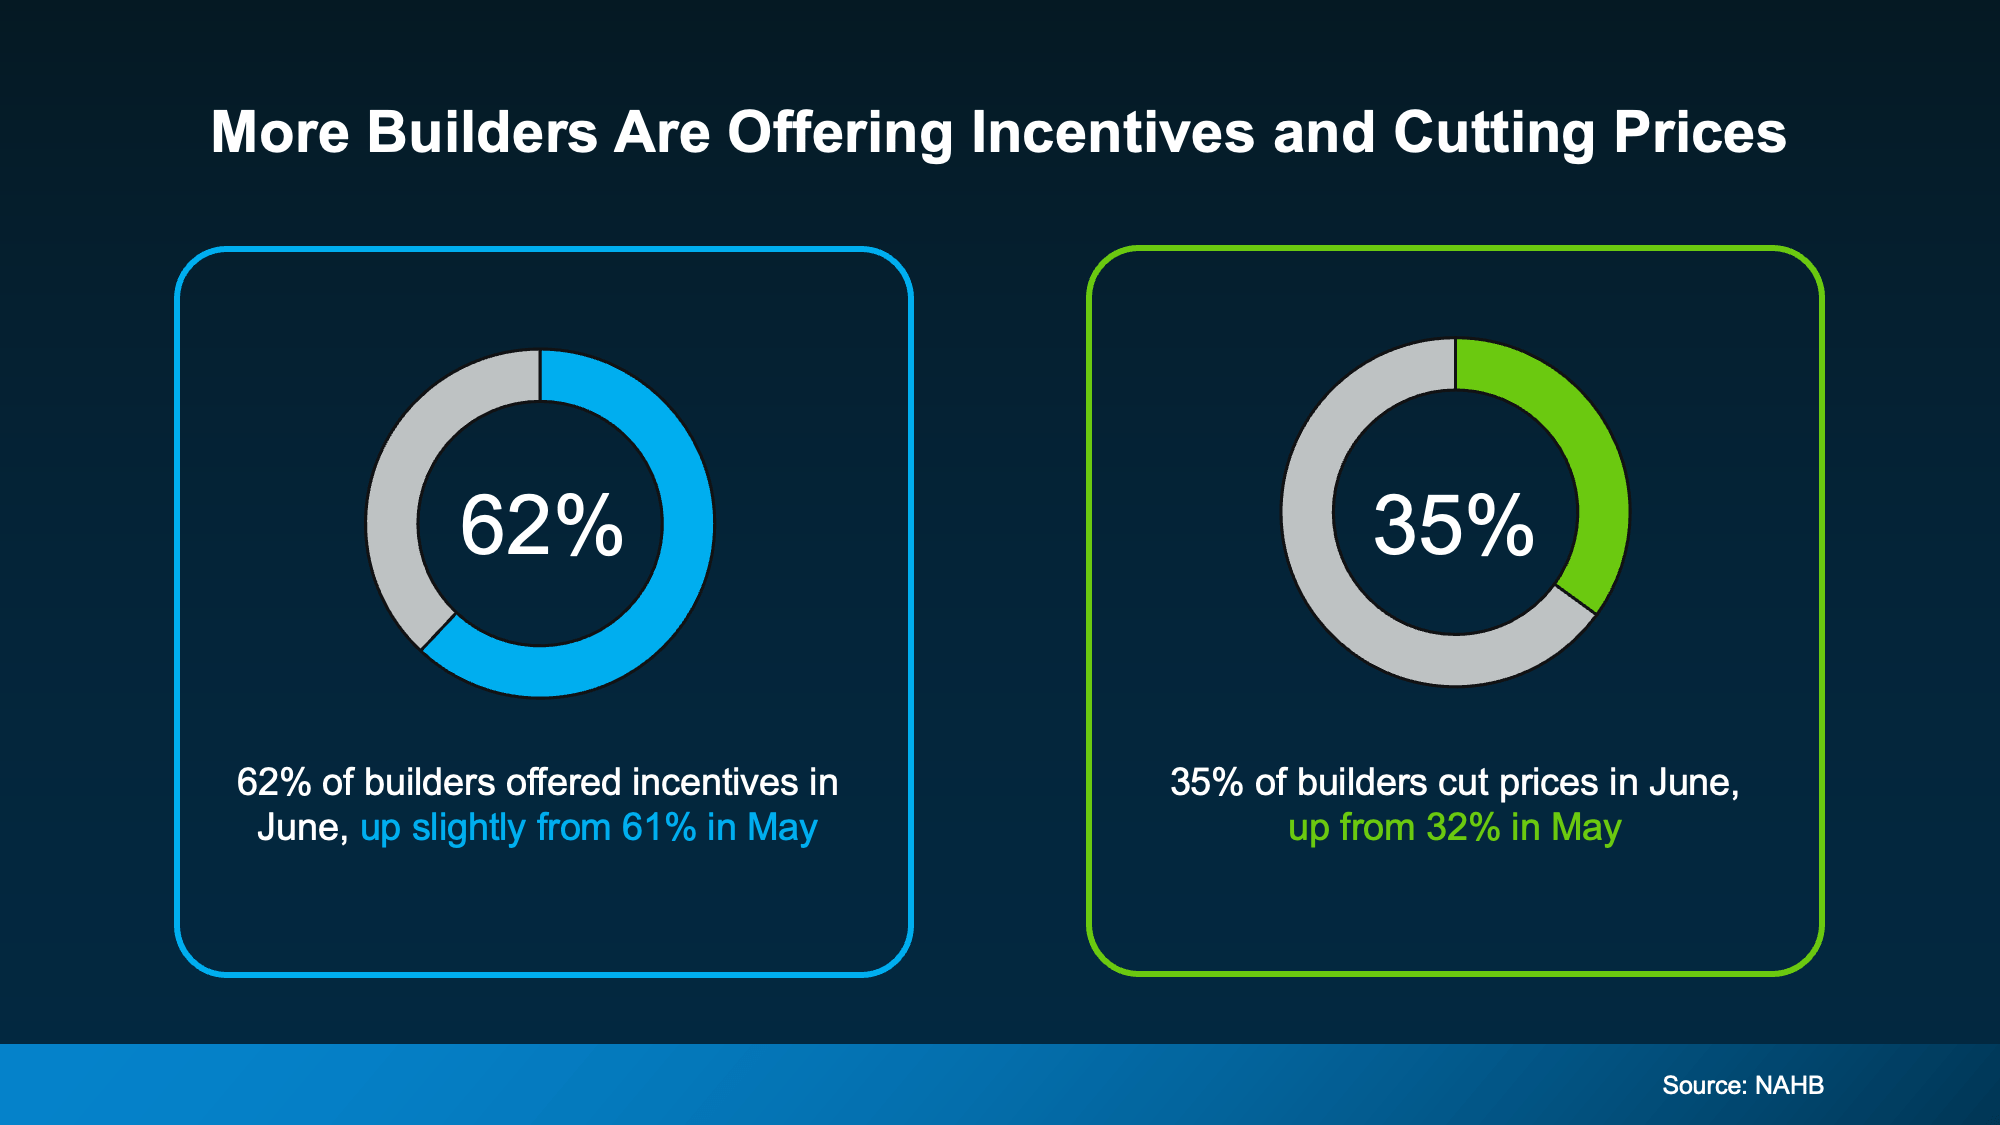
Newly built homes are seeing the same push and pull. According to the National Association of Home Builders (NAHB), 62% of builders are offering incentives right now. And about 35% are cutting prices outright (see chart below):

a screenshot of a graph

Those incentives often look like:

  • Price adjustments

  • Mortgage rate buydowns

  • Free upgrades, like nicer finishes or appliances

Danielle Hale, Chief Economist at Realtor.com, explains why:

New construction has been one of the steadiest parts of the housing market over the past few years, but builders are clearly responding to today’s affordability pressures and higher levels of existing-home inventory.”

Even builders, who many people think rarely negotiate, are competing on price and perks. They have been for over a year now. The same data shows this is the 15th straight month where more than 60% of builders have offered incentives to sweeten the deal. And that’s significant.

What This Means for Your Move

If you’re buying, this is a good time to ask. Whether you have your eye on an existing house or a newly built home, there’s a chance the seller or builder will meet you partway on price, terms, or both.

If you’re selling, expect buyers to ask. Even builders of brand-new homes are making concessions more often than not right now. Holding firm on every term could mean more time on the market, or a lost sale altogether.

Bottom Line

Sellers and builders are both giving buyers more to work with this year. A local agent can tell you what to expect in concessions and incentives based on inventory and competition in your local market.

What To Expect from the Housing Market in the Second Half of 2026

Posted by
What To Expect from the Housing Market in the Second Half of 2026 Simplifying The Market

If the first half of this year has left you feeling stuck, you’re not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.

That’s why so many people are asking the same question: Will the second half of the year be any better for the housing market?

While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here’s what to watch.

Mortgage Rates Could Be Near a Turning Point 

One of the biggest reasons mortgage rates haven’t come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?

Oil prices have already started coming back down.

That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.

Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:

a graph showing the price of a mortgage rate

It’s too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.

And that’s good news for anyone thinking about moving. The first half of the year tested everyone’s patience. The second half may finally reward it.

Home Prices Could Pick Back Up

A lot of people want home prices to fall too. But that’s not what most forecasts show.

While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.

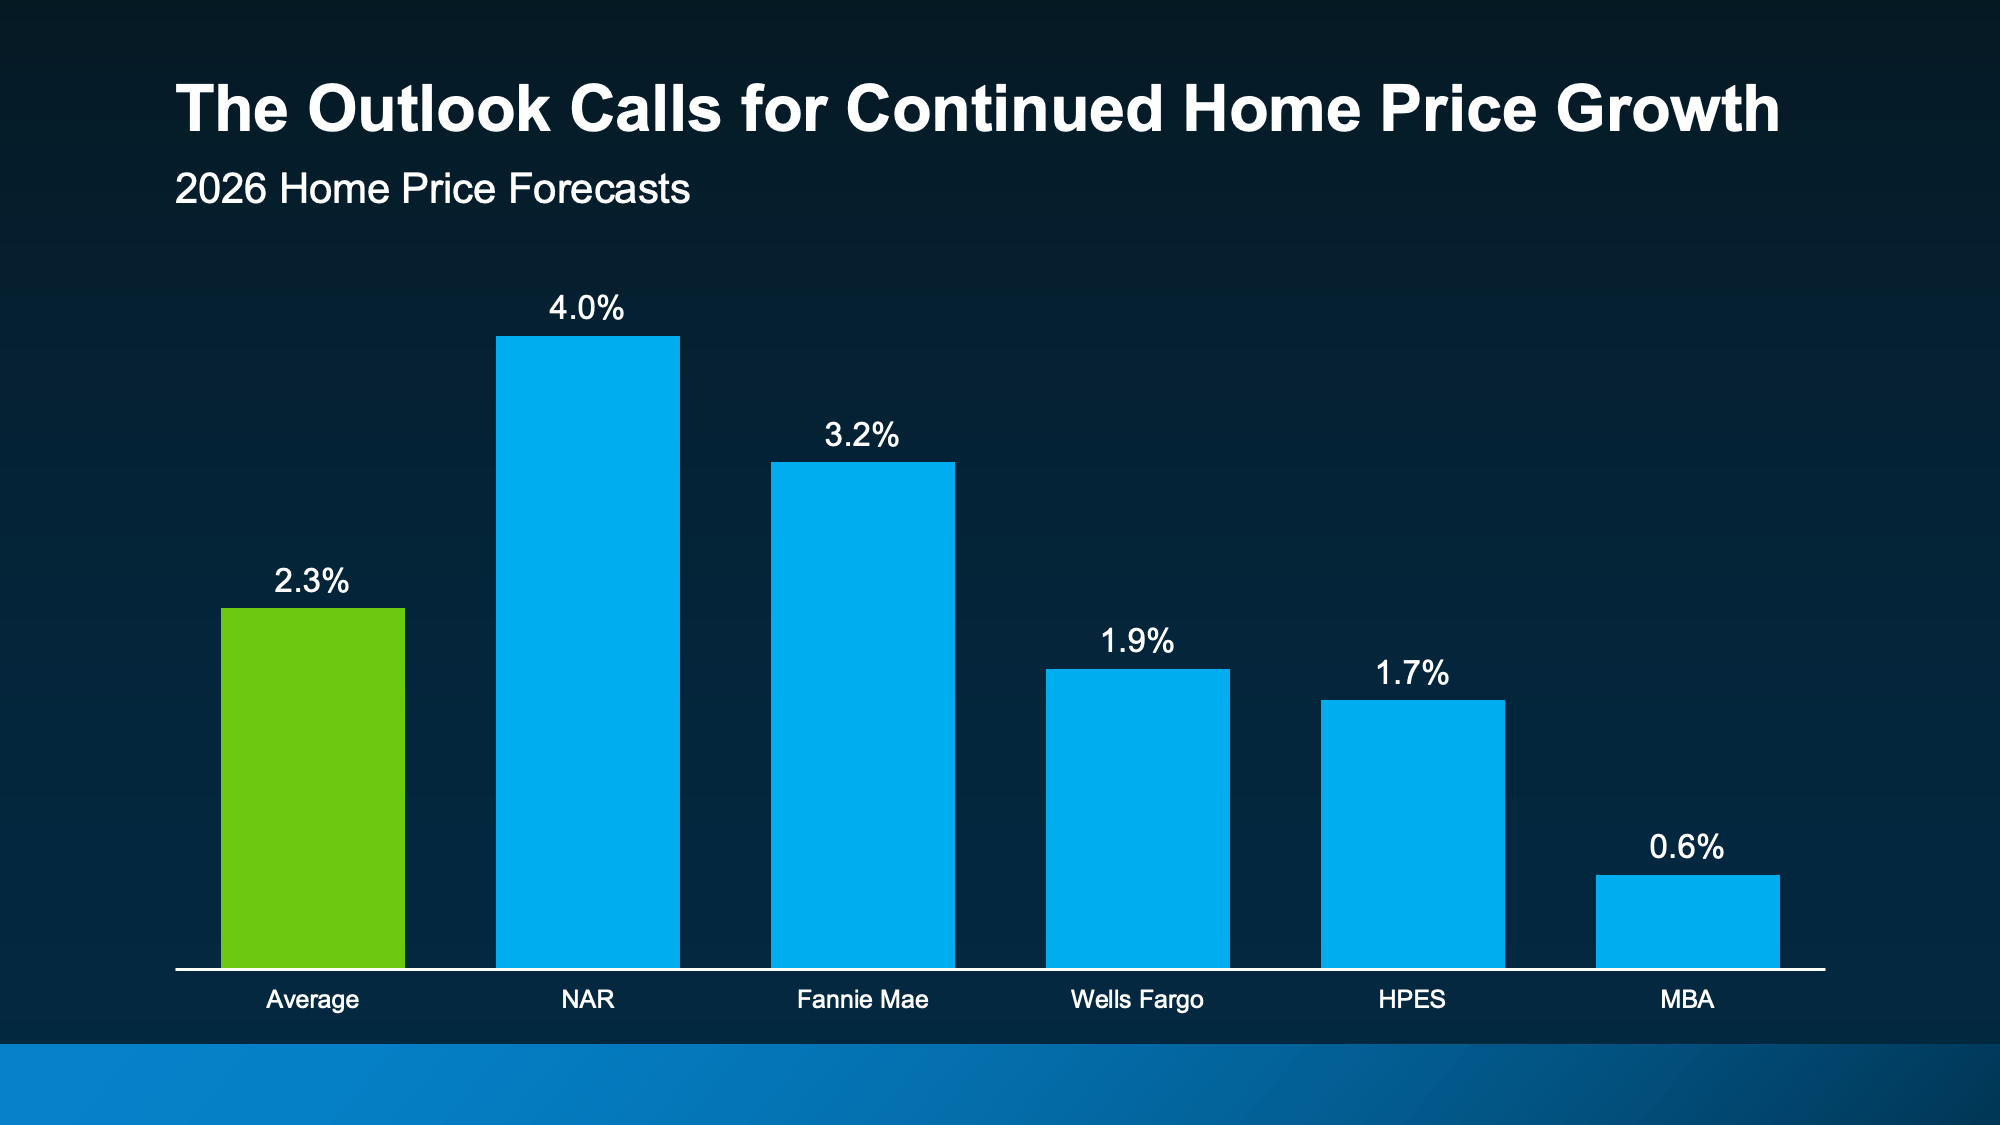
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):

a graph of blue rectangular objects

What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.

Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.

Here’s why that’s possible.

The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.

That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.

More Homes Are Expected To Sell

If you’ve been wondering why the housing market has felt quieter lately, you’re not imagining it. Home sales have been slower than many experts expected. But that doesn’t mean people have stopped wanting to move.

A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon. 

If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:

Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.” 

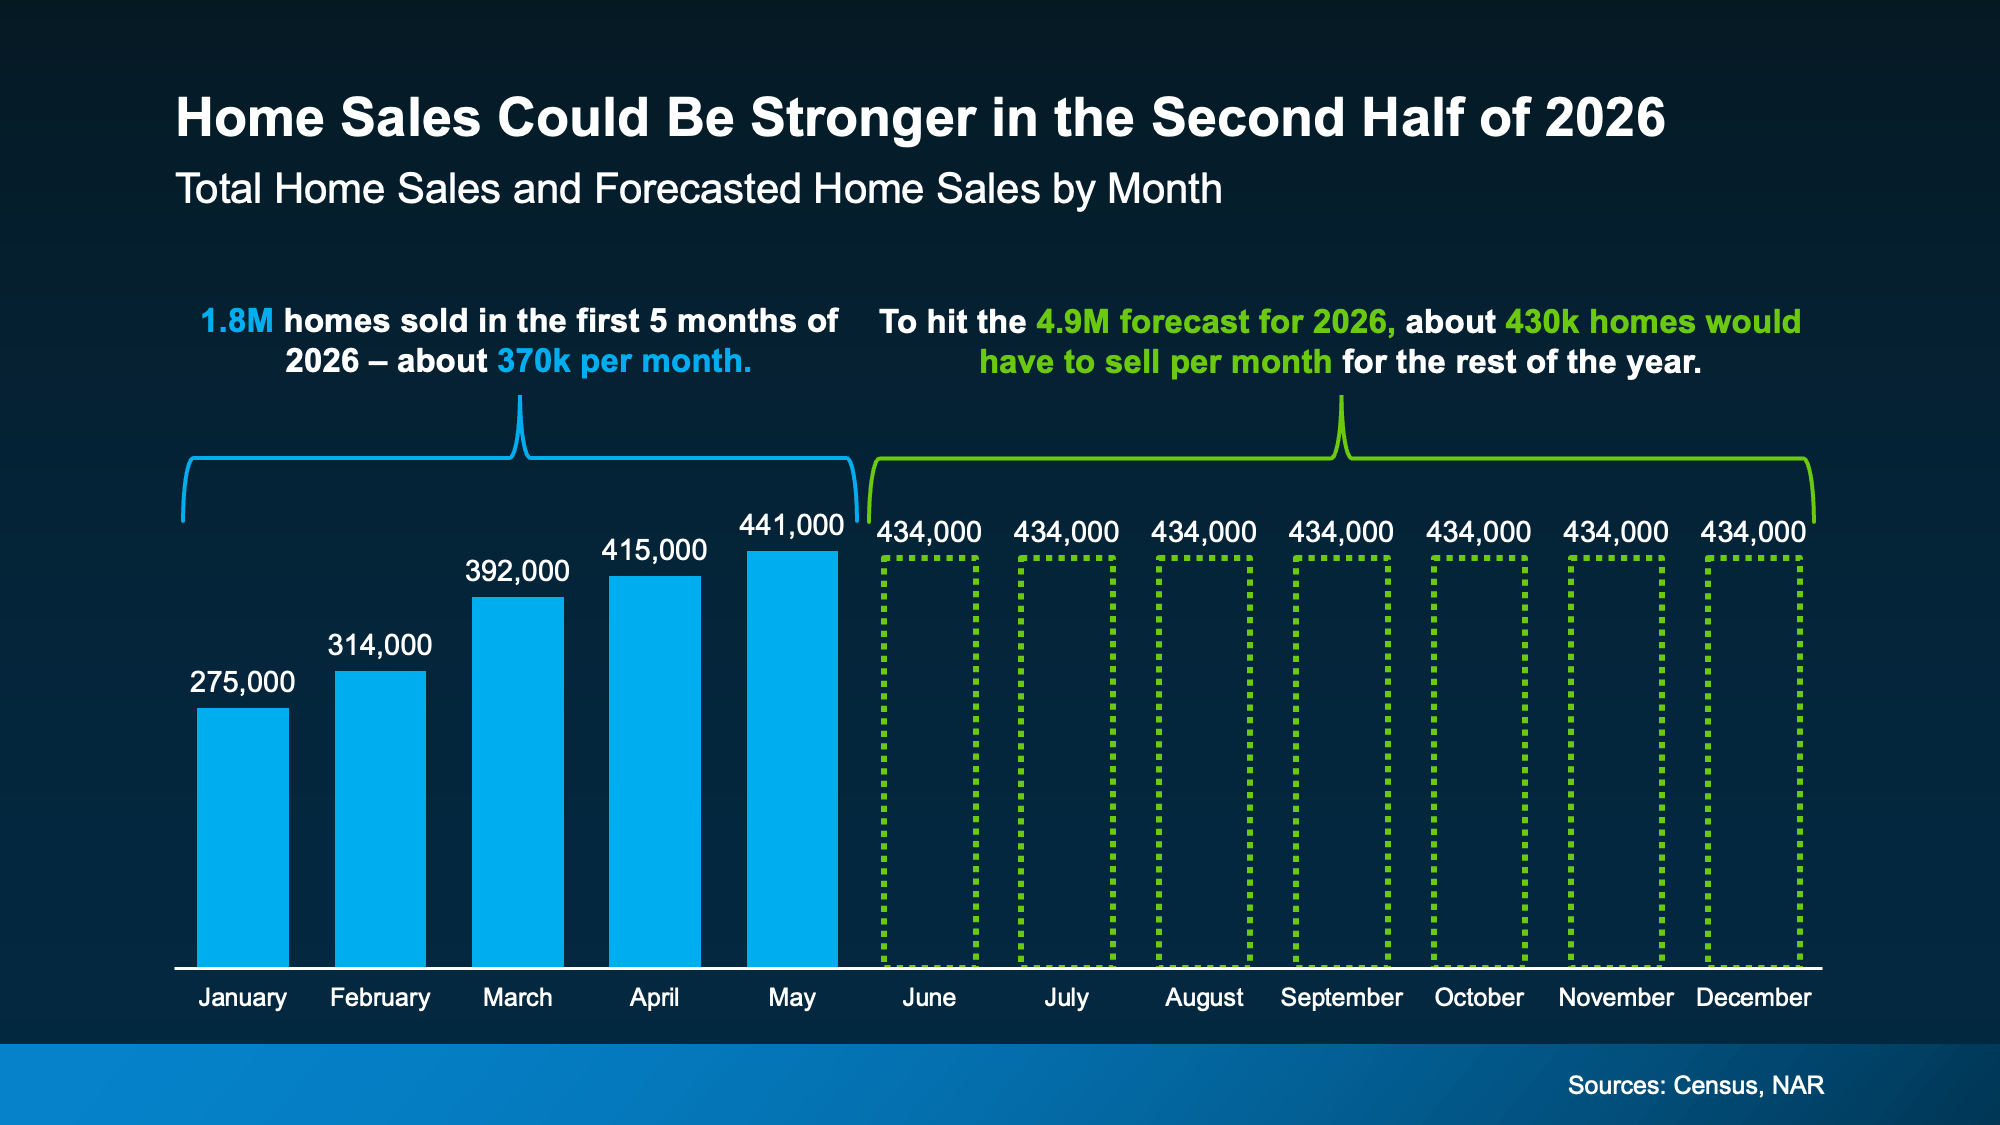
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):

a graph of sales and statistics

In fact, each month for the rest of 2026 would have to come close to matching the best month we’ve had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.

More people will finally make their move happen – and you’ve got the chance to be one of them.

Bottom Line

The second half of the year probably won’t be perfect. But it could be better.

Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you’ve been waiting for signs of progress, this is it.

If you want to understand what these forecasts mean for your plans and what’s happening in your local market, connect with an agent.

What Buying or Selling a Home Gives Back to Your Community

Posted by
What Buying or Selling a Home Gives Back to Your Community Simplifying The Market

Buying or selling a home is a big financial decision. And right now, it feels even bigger. Inflation is high, costs are high, and you want to be sure the timing is right before you make your move. 

But if you do decide to go for it, whether you’re buying or selling, here’s something reassuring to hold onto. Not only does your move change your own life, but it also gives your whole community a boost.

Real estate is a huge part of the economy. In 2025, it added up to about $5.6 trillion, according to the National Association of Realtors (NAR). A good share of that comes from everyday people buying and selling homes, just like you.

Your Move Puts Real Money Into the Local Economy

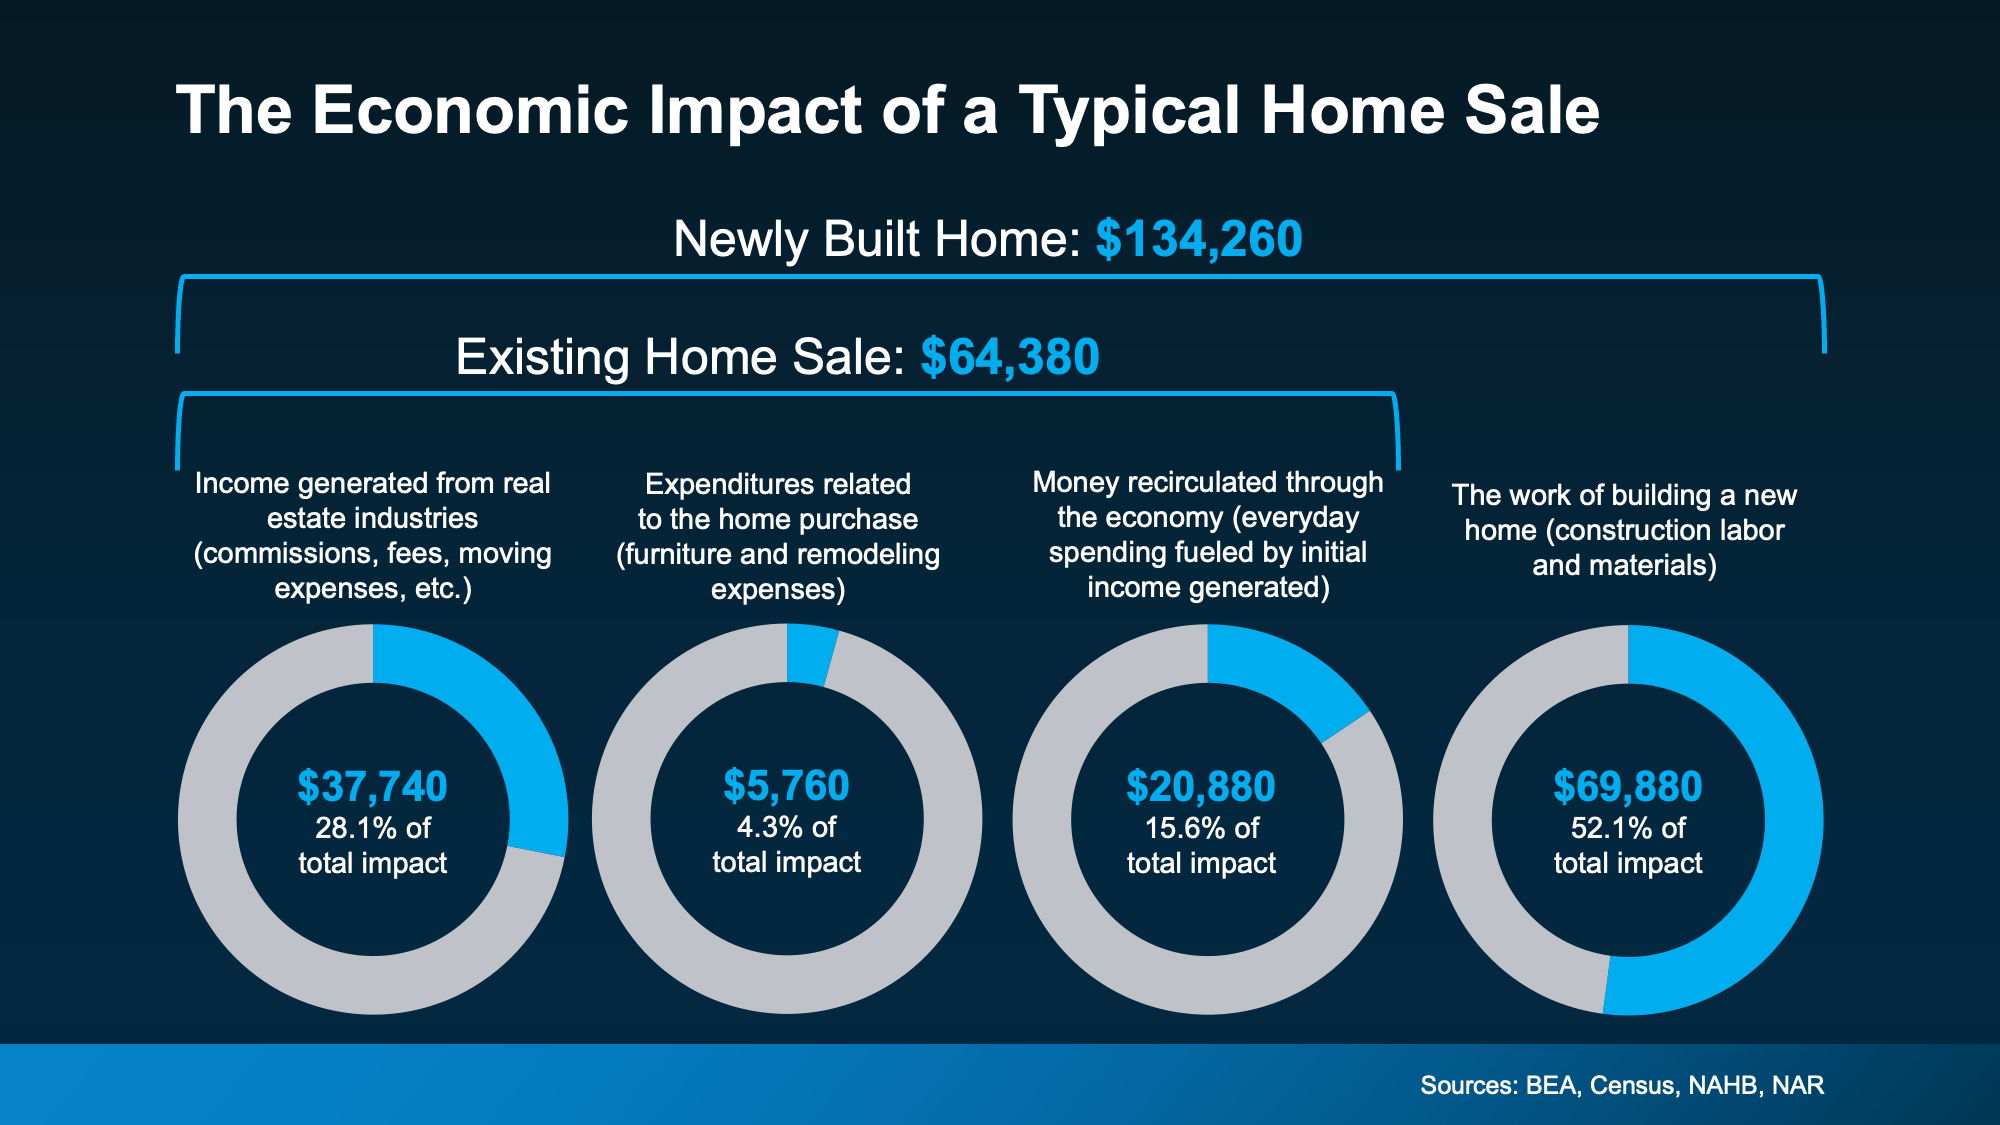
Every sale sends money flowing through your area. NAR data shows that buying an existing home (one that’s already been lived in) adds about $64,000 to the local economy. Buy a newly built home, and that number climbs to more than $134,000 (see graph below):

a diagram of a home sale

Over half of that comes from the work of building the home itself. The rest flows to real estate services, like agent and lender fees, plus what you spend settling in afterward, on things like furniture and remodeling.

And the money doesn’t stop there. As local businesses earn it, they spend it again in your area, so a single sale ripples further than the sale price alone.

One Sale Keeps a Lot of People Working

Behind every sale is a whole network of people doing their jobs. Contractors, lenders, inspectors, movers, and more. When you buy or sell, you help keep them busy. Lawrence Yun, Chief Economist at NAR, puts it this way:

Increased home sales mean more economic activity — lawn care, furniture purchases, moving services, mortgage originations and other related business activities all get a boost.

So, your move supports your neighbors’ livelihoods, too. The deal that gets you into your next home also helps a local crew make payroll. In a year when every paycheck counts, that’s no small thing.

Your Local Impact May Be Even Bigger

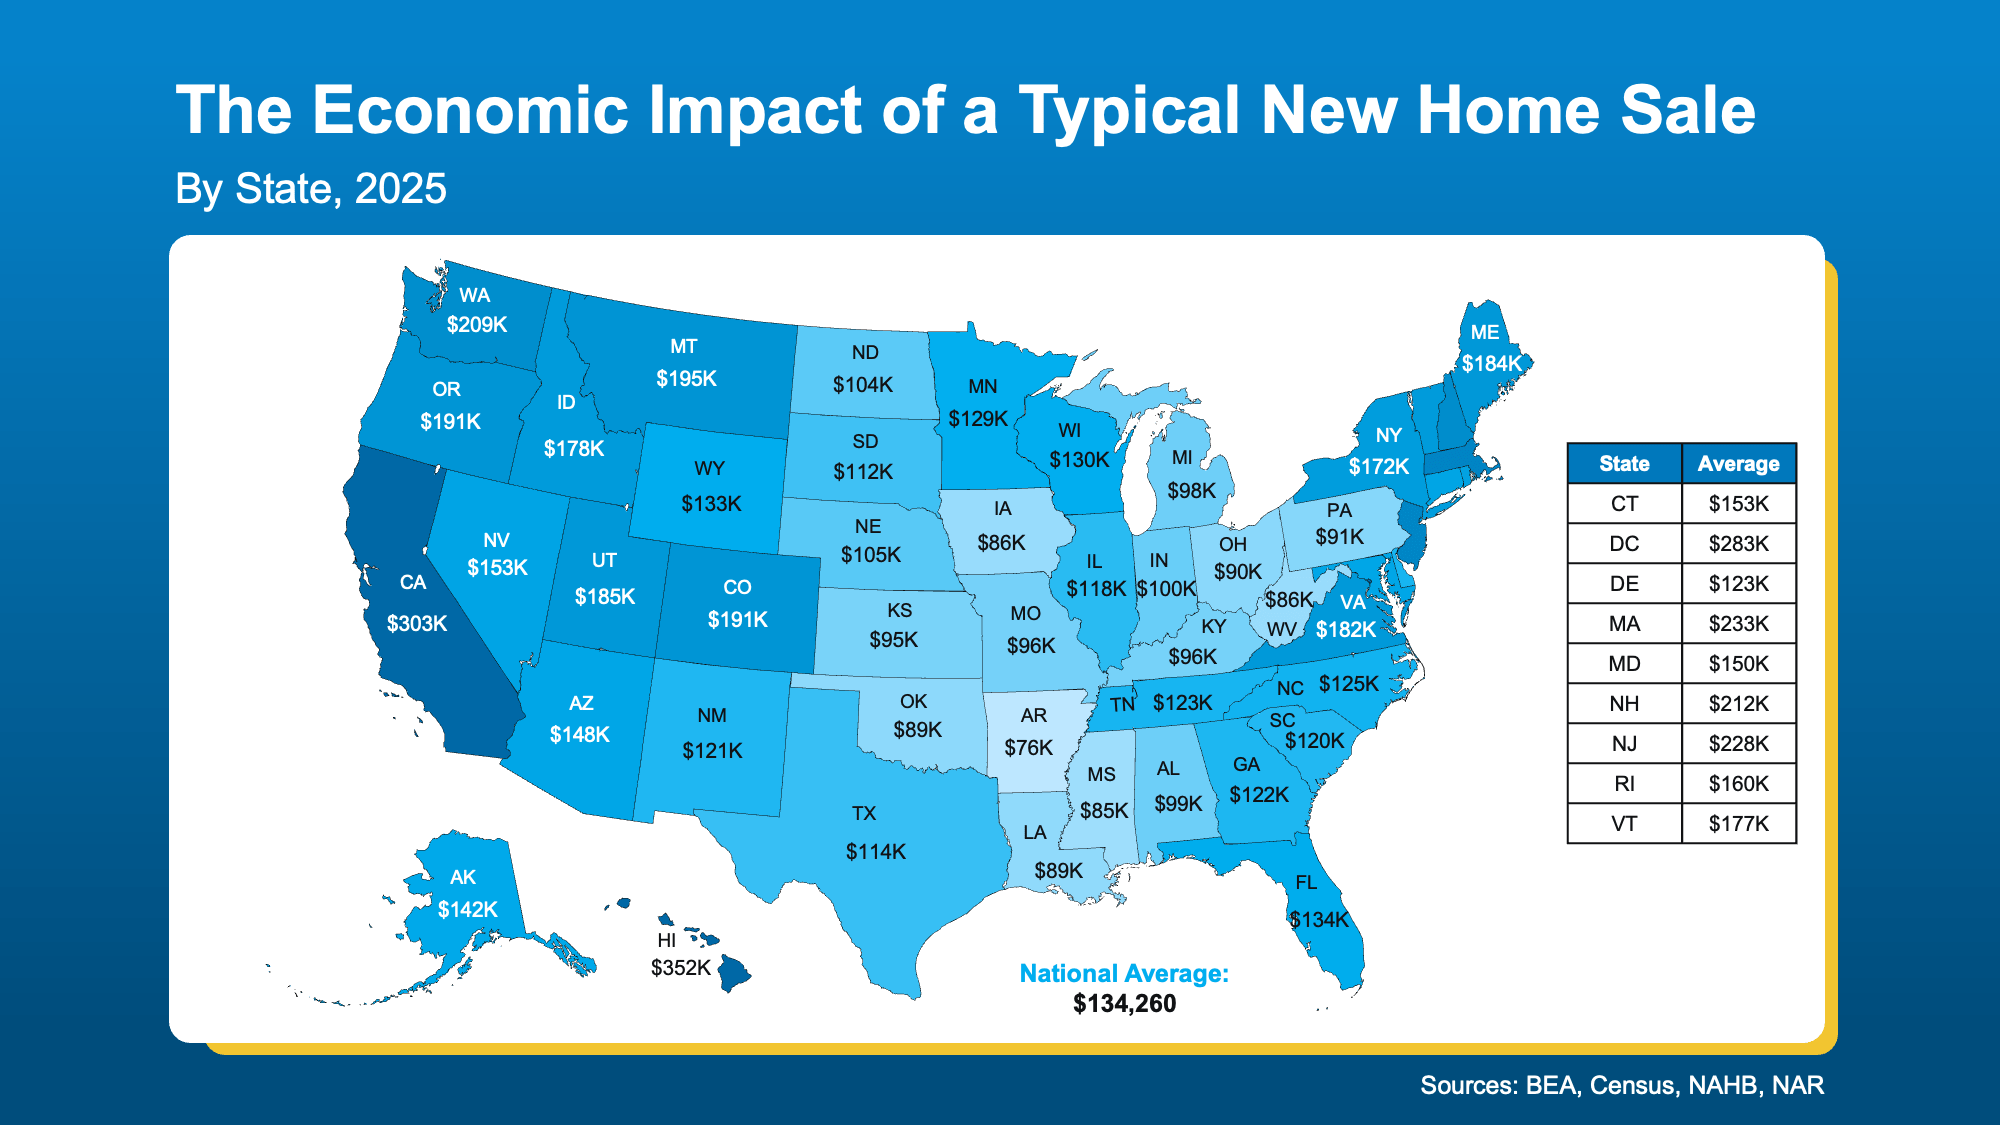
What your move financially adds to your community depends a lot on where you live. To help you see how it can vary, here’s a look at the impact of a typical newly built home sale by state.

The national average for a newly built home is about $134,000, but some states see far more (see map below):

a map of the united states

In California, a single sale adds more than $300,000 to the local economy. In Hawaii, it’s over $350,000. Even in the most affordable states, the number lands in the tens of thousands.

Want to know what a move would mean where you live? A local agent can show you the figure close to home.

Bottom Line

Moving is both a personal milestone and an investment in your community. So, if the time is right for you, connect with a local agent. You’ll make a difference for more people than you know.

The Housing Market Is Stronger Than You Think

Posted by
The Housing Market Is Stronger Than You Think Simplifying The Market

You’ve probably heard plenty of doom and gloom about the housing market lately. High rates. Stretched budgets. Headlines that make buying or selling sound like a terrible idea. But the data tells a very different story. 

This isn’t 2020 or 2021. It was never going to be. Those were the “unicorn years” – historic low mortgage rates, bidding wars on everything, homes flying off the market in days. That kind of market was a once-in-a-generation anomaly, not a baseline. So, when people compare today to that, of course it looks rough.

But compared to almost any other housing market in modern history? This one is holding up remarkably well.

Homeowners Are Sitting on a Mountain of Equity

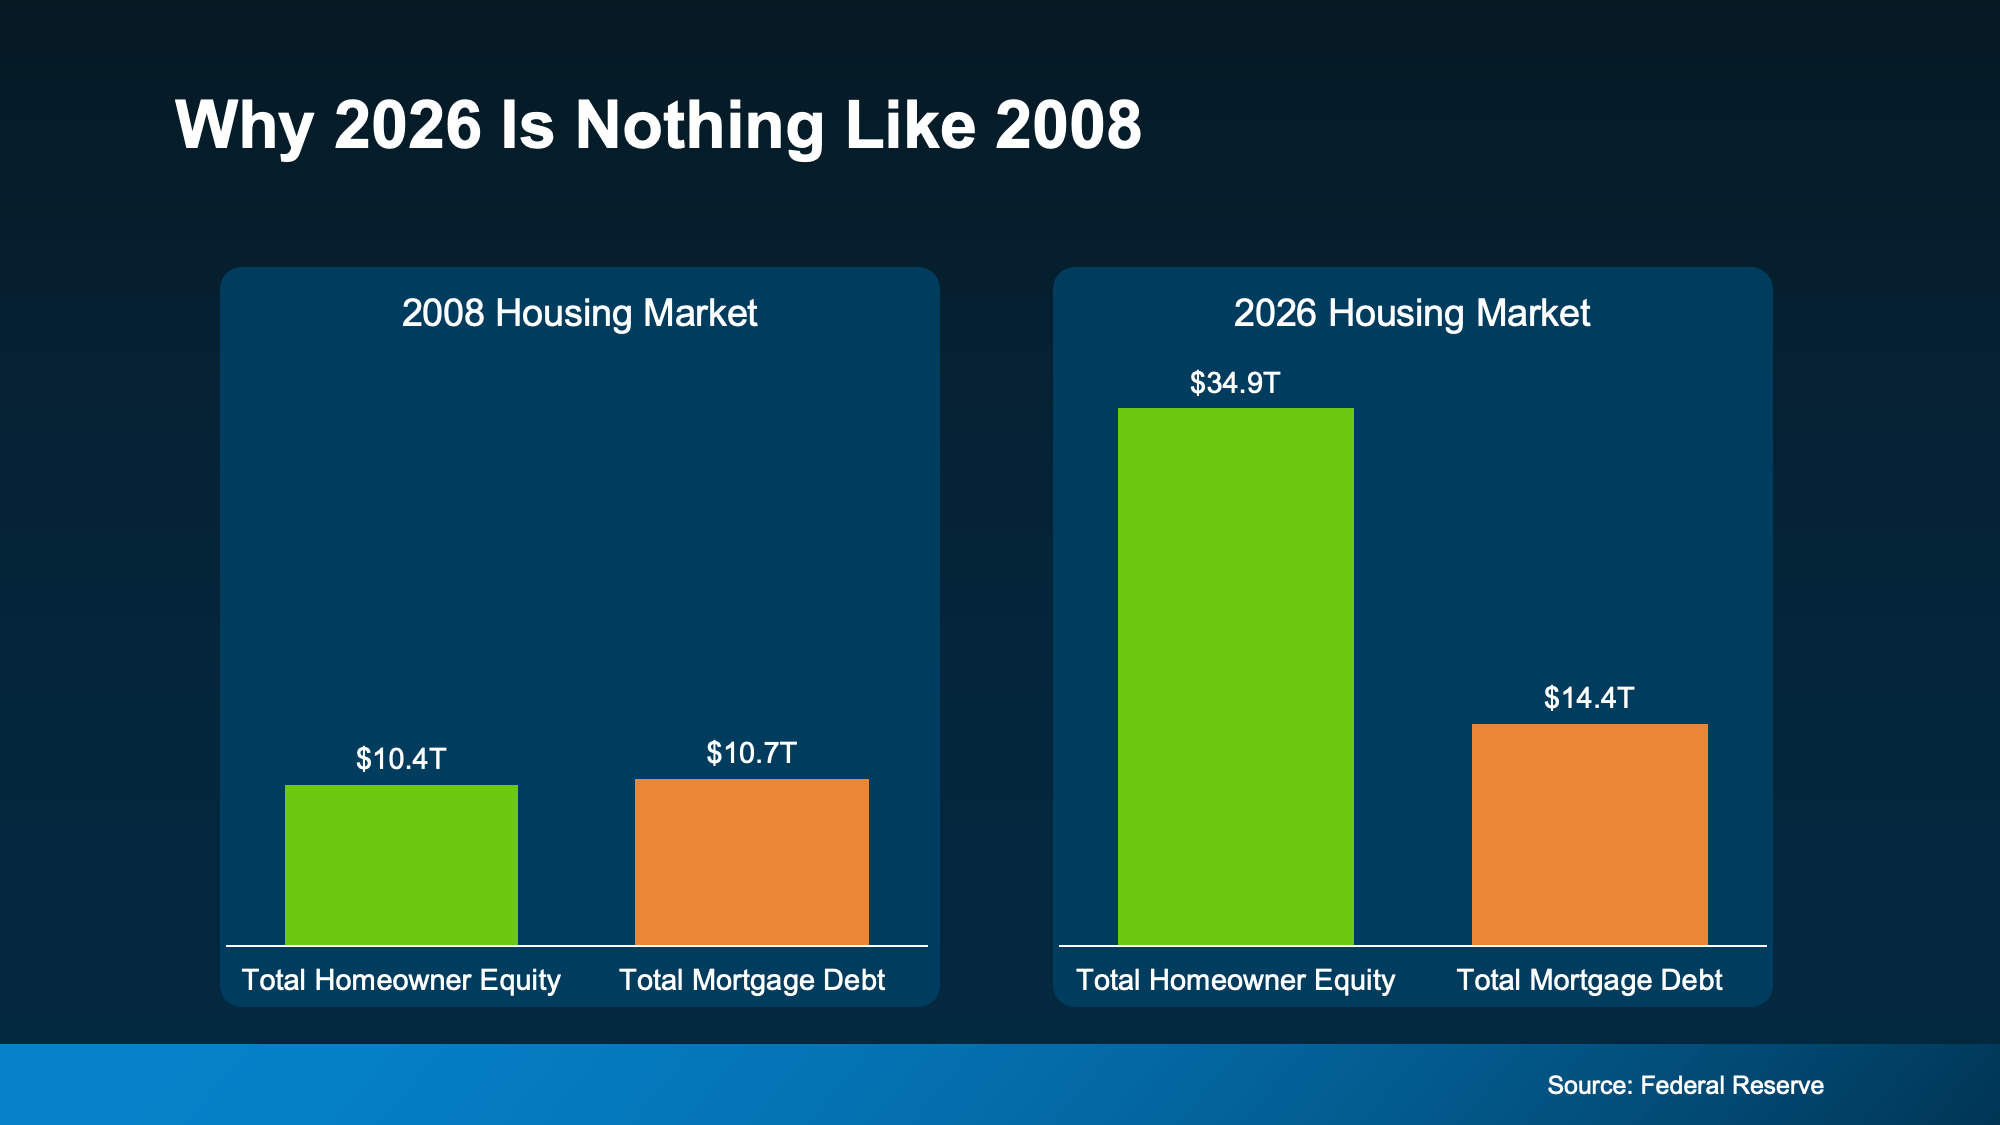
One of the biggest reasons this market hasn’t cracked is the financial strength of the American homeowner. According to Federal Reserve data, homeowner equity and mortgage debt were nearly identical in 2008. That means, if someone hit a rough patch, they had almost nothing to fall back on. That’s what made that crash so bad.

Today? Total homeowner equity across the country sits at $35 trillion – dwarfing total mortgage debt (see graph below):

a graph of a marketThat gap means most homeowners aren’t stretched thin or one bad month away from trouble. They own a meaningful chunk of their home and that gives them options. If they needed to sell, many could because they have a cushion. And that cushion grows over time.
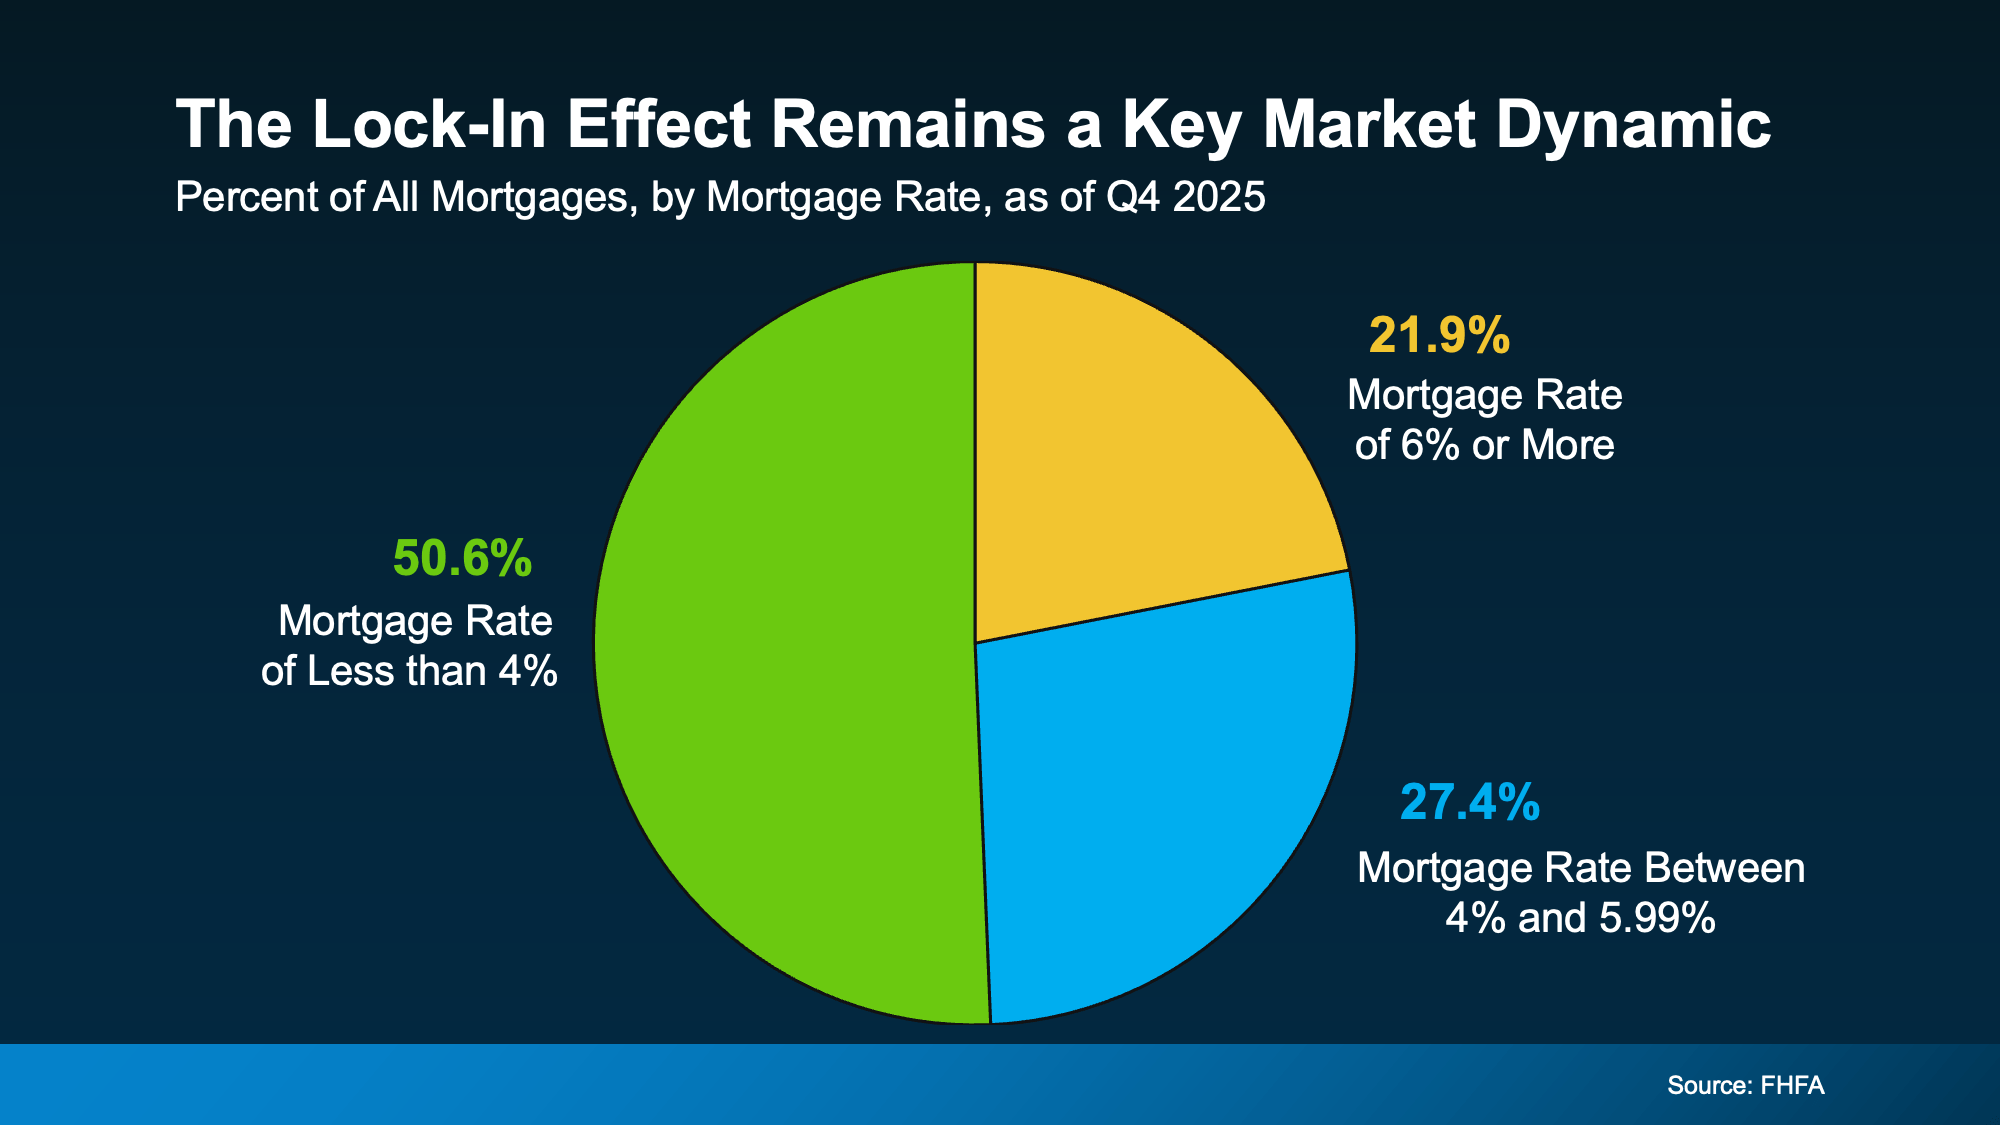
  • Realtor.com found that homeowners who’ve been in their home just 5 years have built up around $180,000 in equity on average. Stick around 6-10 years, and that jumps to over $340,000.

  • Data from ATTOM and the Census shows two-thirds of homeowners either own their home outright or have more than 50% equity.

That’s not a fragile market. That’s a population of homeowners who are financially positioned to sell, to stay, or to make their next move from a place of strength rather than pressure.

Low Rates and Low Foreclosures

At the same time, Federal Housing Finance Agency (FHFA) data shows more than half of all active mortgages still carry a rate below 4% (see graph below): 

a chart with text on itThat’s a big reason inventory stays tight. Those homeowners aren’t in a rush to trade their rate for a higher one. They’re sitting comfortably in a strong financial position, not scrambling.
That comfort shows up in the foreclosure numbers, too. Despite a slight recent uptick, foreclosure volumes remain dramatically below historical norms, according to ATTOM. Homeowners aren’t losing their homes in droves. They have equity, they have breathing room, and most have options that keep them out of financial distress.

Prices Are Stabilizing, Not Crashing

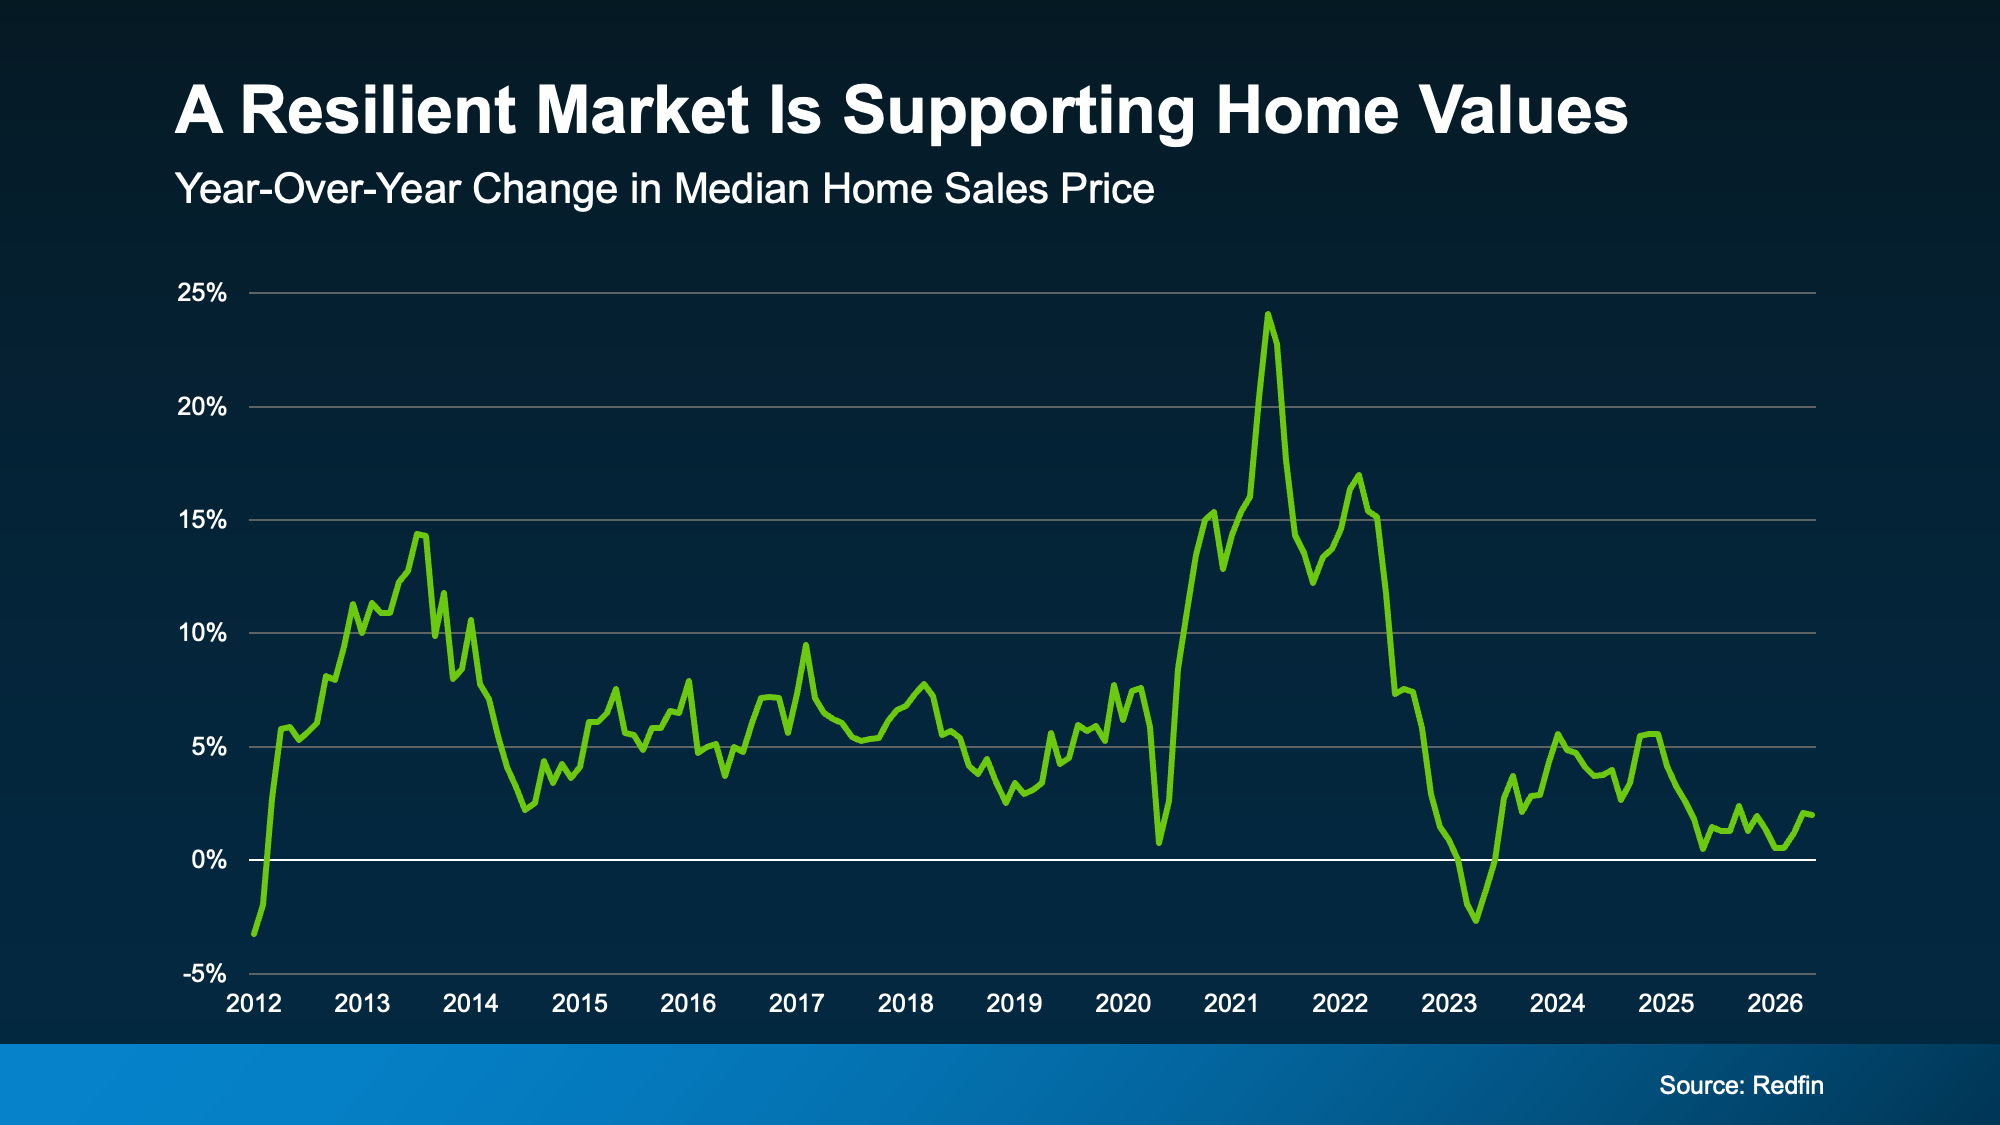
Here’s another point on the resilience of the market. Redfin research shows home prices are still rising, but the pace has slowed, now closer to 2% year-over-year nationally (see graph below):

a graph of a line graphThat slowdown is good news, as Daryl Fairweather, Chief Economist at Redfin, explains:
“We’re in the middle of a long-term housing market correction, not a housing market crash. After the pandemic-era frenzy sent prices soaring and inventory to historic lows, the market needed a reset.

Bottom Line

This market isn’t broken, and waiting for a crash that isn’t coming has a cost. Every month spent on the sidelines is a month someone else is building equity, locking in a price, or getting ahead of what most experts expect to be a housing surge once broader economic conditions settle.

Whether you’re thinking about buying or selling, a local real estate agent can help you figure out what this market means for your specific situation and what your next move could look like.

The 1 Factor That Explains Everything Happening with Home Prices Right Now

Posted by
The 1 Factor That Explains Everything Happening with Home Prices Right Now Simplifying The Market

You’ve probably heard that home prices are cooling off. And that’s true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.

Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what’s causing all of that variation? 

It All Comes Down to Inventory

Here’s the simple version:

  1. When there are more homes for sale, buyers have options.

  2. More options, means less competition.

  3. Less competition means sellers can’t push prices as high.

On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.

That dynamic is playing out right now in a really visible way across the country. 

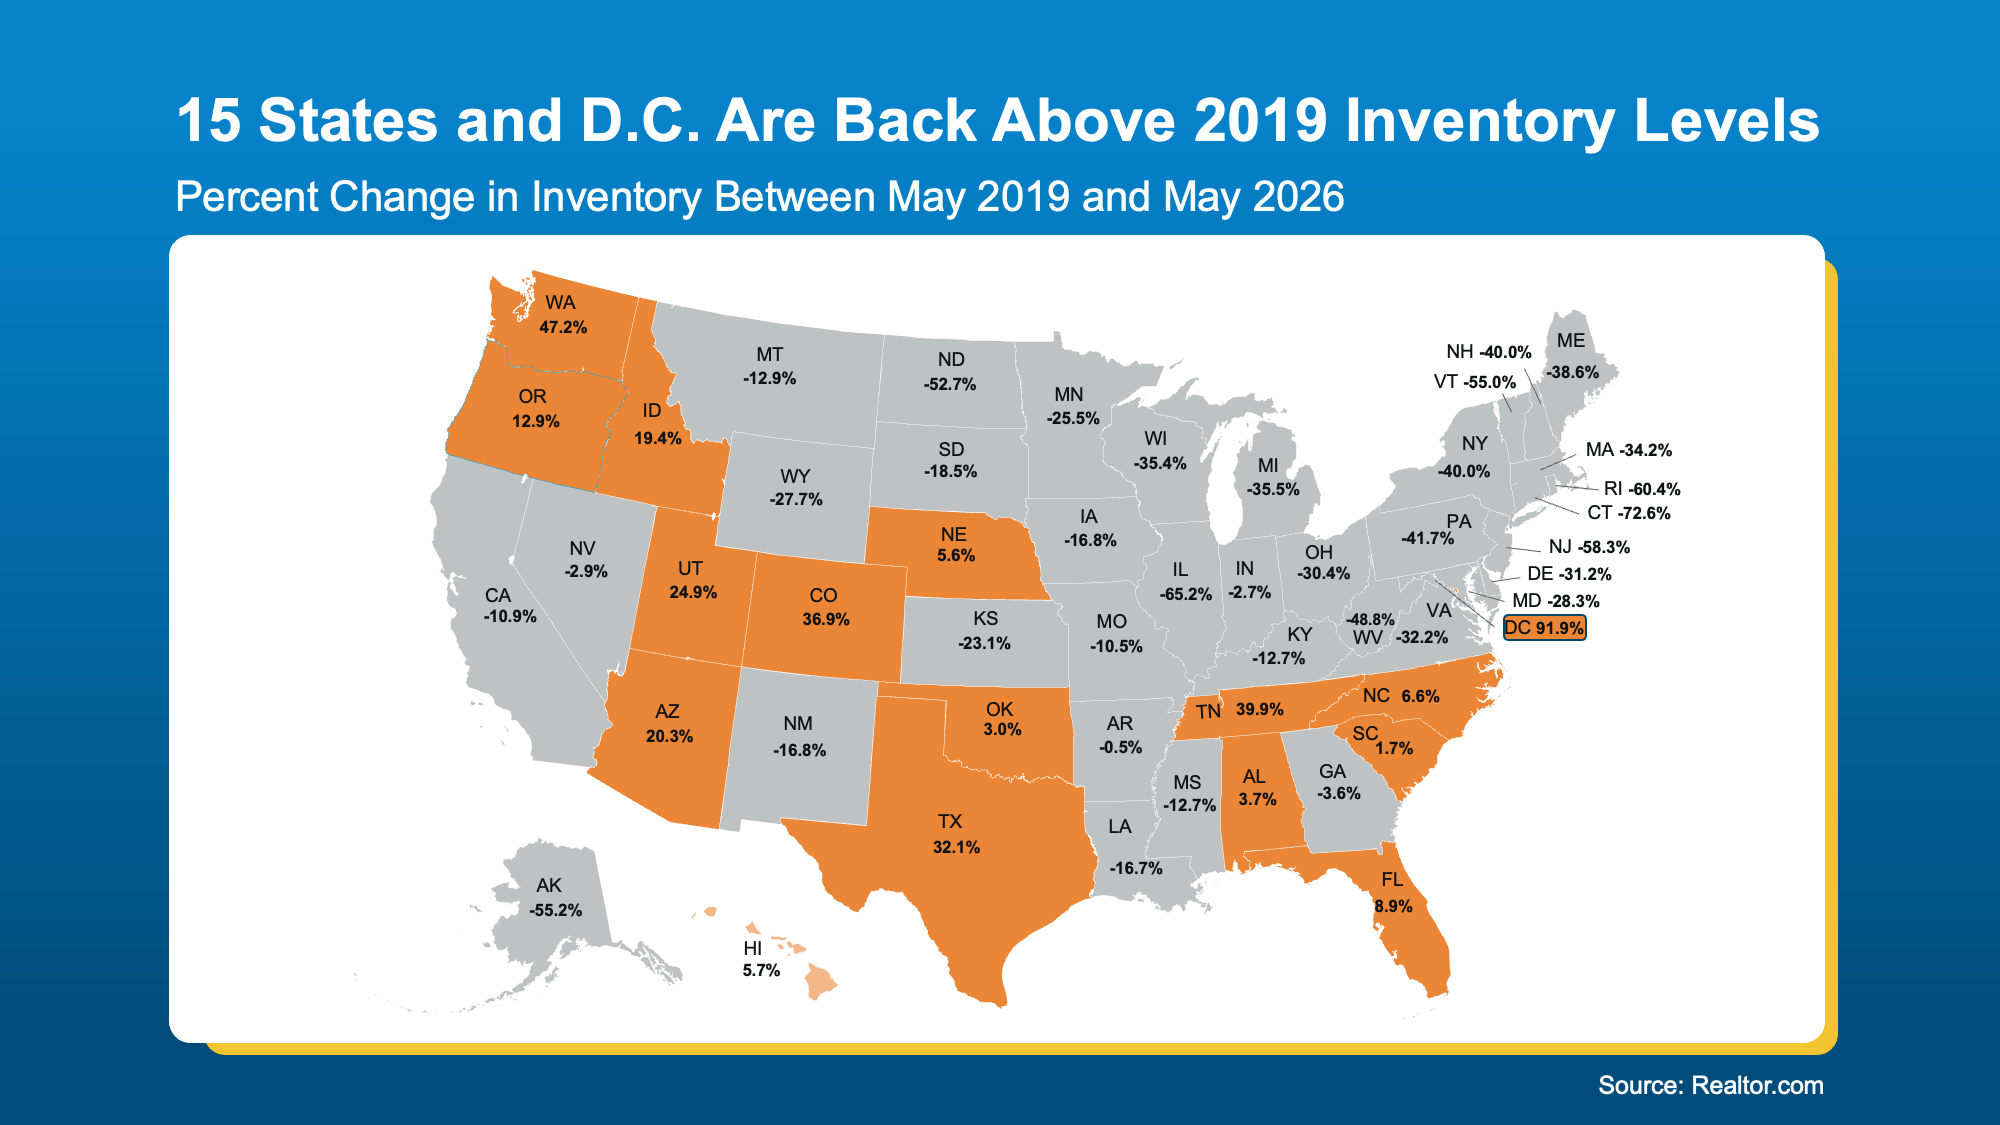
Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:

“Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.

In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing.”

The Maps Say It All 

Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.

But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.

According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):

a map of the united statesNow, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what’s happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map). 
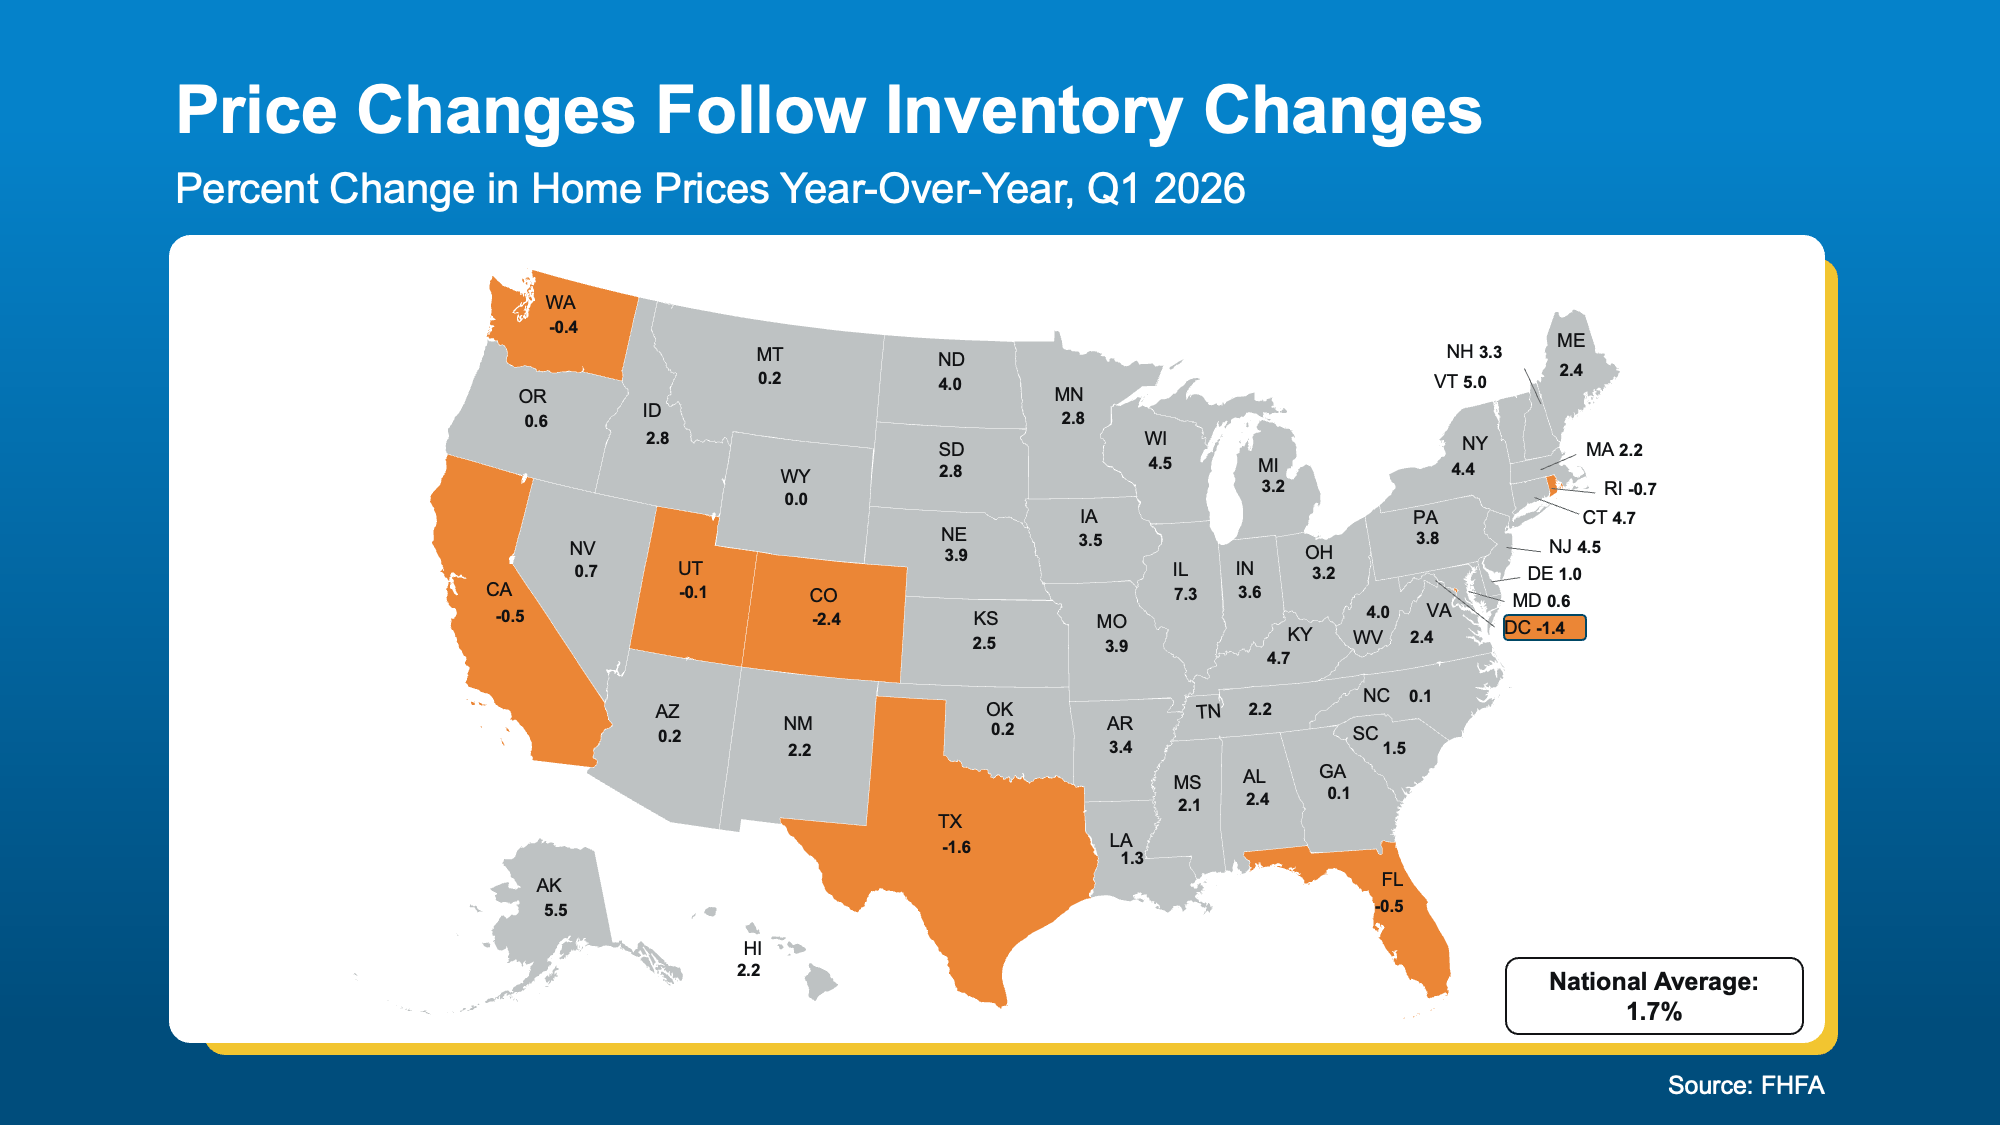
See how those line up pretty closely with the areas seeing more homes for sale today?

The overlap isn’t a coincidence. It’s cause and effect. 

a map of the united states

The national average of 1.7% price growth is accurate, but it’s an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.

What This Means If You’re Buying or Selling 

If you’re a buyer, the market you’re shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you’re still likely facing a lot of competition.

If you’re a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you’re in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that’s where a local real estate agent earns their keep.

Bottom Line

When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.

Reach out to a local real estate agent today and work together to build a plan that fits your market.